
Safe Haven Capital Flow Regimes
US Exorbitant Privilege & NIIP Valuation Effects Across Dollar Cycles
Coined in 1965 by Valéry Giscard d’Estaing and quantified by Gourinchas and Rey, America’s "Exorbitant Privilege" operates like a giant global venture-capital hedge fund: borrowing cheaply in safe US dollar debt while earning high returns in foreign-currency equities and FDI.
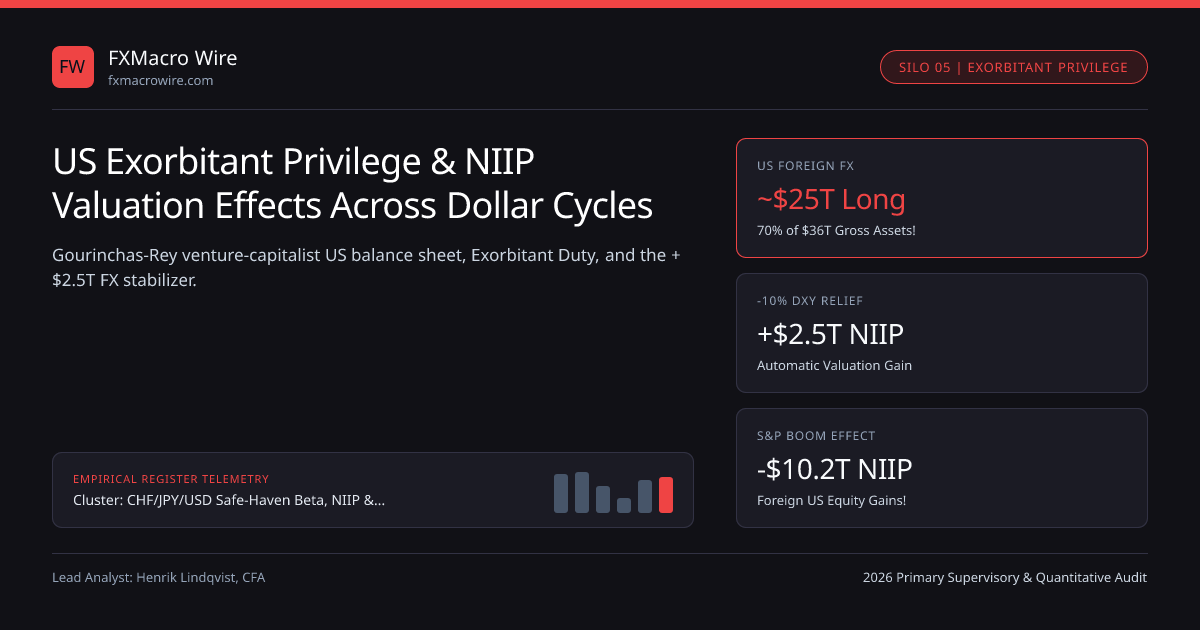
Here is one of the greatest macroeconomic paradoxes of modern history: the United States carries a Net International Investment Position (NIIP) of roughly -$21.5 trillion (-72% of GDP)—meaning foreigners own $21.5 trillion MORE US assets than Americans own abroad—yet up until the post-2023 5% rate surge, America's annual Net Primary Investment Income in the Balance of Payments remained POSITIVE (+$120B to +$220B/year for decades!)!
How can someone who is $21.5 trillion net in debt earn MORE investment income from their smaller assets than they pay out on their massive liabilities? Economists Pierre-Olivier Gourinchas and Hélène Rey solved this riddle by proving that the United States balance sheet operates as the world's "Global Venture Capitalist" (borrowing short/safe in low-yield USD Treasuries & deposits inside $13.22T COFER reserves while investing long/risky in high-return foreign FDI & equities)—paired with a symmetric crisis counterweight called "Exorbitant Duty"!
Return Privilege vs Valuation Channel: Two Halves of Gourinchas-Rey!#
Institutional macro researchers across ECB, BCBS / BIS, Banque de France / ACPR, and Wall Street strategy desks (Blocksize Capital, Bequant, CMC Central) decompose US external sustainability across DXY cycles into two distinct balance-sheet engines:
- The Return-Differential Engine (Exorbitant Privilege — ~+2.0% to +3.3%/yr Excess Return!): Historically (1973–2024), US multinationals (Apple, Microsoft, Pfizer, Exxon) earned ~6.8%–8.5% annualized returns on outward Foreign Direct Investment, whereas foreign central banks and insurers earned ~2.5%–3.8% on US Treasuries and Agency MBS!
- The Currency Valuation Channel (Automatic Debt Stabilizer When USD Depreciates!):
- 92%+ of US External Liabilities (~$57.5T) are denominated in US DOLLARS!
- ~70% of US External Assets (~$36.0T -> ~$25T in foreign FX!) are denominated in FOREIGN CURRENCIES (EUR, GBP, JPY, CAD, EM)!
- Run the shocking math: *Whenever DXY depreciates by -10%, the USD value of America's foreign assets JUMPS by +$2.5 TRILLION (+$25T 10%) while US dollar liabilities change by $0—wiping out $2.5 trillion of US net external debt overnight without a single cent of austerity or default!**
"Exorbitant Duty": Why the World Willingly Pays America's Insurance Premium!#
If foreigners earn 250 bps less on US Treasuries than Americans earn abroad, why haven't foreign central banks and pensions revolted? Gourinchas, Rey & Govillot (2010) proved the global insurance bargain:
- During calm bull markets, America collects the insurance premium (Exorbitant Privilege).
- The instant a global catastrophe hits (2008 GFC, 2020 Pandemic), DXY surges +12% while 10Y US Treasuries rally +8% (Left-Wing Dollar Smile, Dollar Smile framework)!
- Foreigners' safe USD bonds soar in local-currency terms while America's foreign-currency equity assets plunge—transferring $2.5T to $4.0T of net wealth FROM the United States TO the rest of the world at the exact moment foreigners value wealth highest (Exorbitant Duty)!
| Macro Cycle Phase | Spot DXY & Asset Return Action | Impact on US Net IIP (-$21.5T) | Economic Interpretation |
|---|---|---|---|
| 2011–2024 US Tech Boom | S&P 500 +380% vs MSCI EAFE +55%; DXY +35% | US NIIP plunged -$4T -> -$21.5T! | Success Penalty! Foreigners got rich owning Nvidia/Apple; strong USD shrank US foreign FX assets! |
| Global Crisis (2008 / Mar 2020) | DXY +10%, USTs +8%, Global Stocks -30% | US NIIP drops -$3.0T in 1 quarter | Exorbitant Duty: US balance sheet pays out global disaster insurance |
| Soft-Landing USD Bear (2002–07) | DXY -28%, Foreign EAFE/EM Stocks beat S&P | US NIIP IMPROVED despite -5% CA deficits! | Valuation Channel: Weak USD inflates $25T of US foreign-currency assets! |
| 2025–2026 High-Rate Shift | US SOFR/UST yields at 3.8%–4.4% on $9T debt | US Net Primary Income flips near $0 / slight negative! | Higher coupon bill on $9T foreign USTs narrows old income privilege! |
Quantitative Gourinchas-Rey Net Foreign Asset Dynamics & Valuation Channel Formula#
Look at why predicting future 24-month DXY returns from the Cyclical External Imbalance (nxa metric of Gourinchas & Rey) achieved famous out-of-sample forecasting success across G10 macro research:
- ValuationGainUSt = AssetsFX{t-1} * ( - Delta ln(DXYt) + RForeignLocalt ) - LiabilitiesUSD{t-1} * RUSAssetst
- Worked Valuation Stabilization Proof (Why a -12% DXY Cycle Offsets 3 Full Years of -$900B US Trade Deficits!):
- Suppose US runs -$900B/yr Current Account Deficit for 3 years = -$2.70 Trillion cumulative borrowing.
- Simultaneously, over those 3 years DXY falls -12% AND MSCI EAFE outperforms S&P 500 by +4%/yr (+12% cumulative):
- FX Valuation Gain on $25T Foreign-CCY US Assets = $25.0T * (+12%) = +$3.00 Trillion!
- Relative Equity Valuation Gain = ~$1.80 Trillion!
- > Net 3-Year Change in US NIIP = -$2.70T (Trade) + $4.80T (Valuation) = +$2.10 Trillion IMPROVEMENT in US Net Debt!!
The Modern 2026 Twist: Shrinking Net Primary Income as $9T Foreign USTs Roll at ~4%!#
While the FX Valuation Stabilizer is larger than ever (+$25T foreign-currency US assets!), institutional strategists flag one genuine erosion of Exorbitant Privilege in 2025–2026: when US Treasury rates sat at 0.5%–1.5% (2010–2021), paying interest on $8T of foreign-owned Treasuries cost next to nothing; at ~3.8%–4.3% Treasury yields, annual US coupon payments to foreigners topped $340B+/year—pushing America's century-old positive Net Primary Income balance down to ~0.0% / -0.2% of GDP!
Strategic Implication for Multi-Year Dollar Positioning#
Understanding that -$21.5T US NIIP largely reflects S&P 500 equity outperformance connects our safe-haven FX & BoP hub guide, NIIP creditor vs debtor mechanics, unhedged foreign US equity TIC inflows, and US fiscal deficits vs hedged UST demand—showing why the biggest medium-term bear risk to DXY isn't a sovereign bond default, but simply a valuation rotation from expensive US tech equities into cheaper European and Asian stocks across our safe-haven FX & capital-flow regimes hub!
Frequently asked questions
Who coined the phrase "Exorbitant Privilege" regarding the US dollar?
French Finance Minister Valéry Giscard d’Estaing coined "privilège exorbitant" in 1965 under Bretton Woods to criticize America’s ability to finance external deficits in its own reserve currency without gold outflow constraints.
Why does S&P 500 outperformance make America’s Net International Investment Position look WORSE?
Foreigners own ~$17 trillion of US equities (recorded as a US External Liability in IIP accounting!); when Nvidia, Microsoft, and Apple double in price, US "liabilities" jump by trillions even though America didn’t borrow a dime.
What is "Exorbitant Duty" in Gourinchas and Rey’s international macro model?
It is the crisis counterpart to Exorbitant Privilege: because the US is net long risky foreign-currency equities and net short safe USD debt, global crashes cause massive mark-to-market transfers from the US to foreign safe-asset holders.
Why did America’s Net Primary Investment Income shrink near zero in 2024-2026?
Refinancing ~$9 trillion of foreign-held US Treasury bills and notes from post-GFC 1% rates up to ~4.0% yields raised annual US interest outlays to foreigners by over $250 billion per year.
Publication record
- Published
- 13 November 2026
- Updated
- 15 November 2026
- Author
- Henrik Lindqvist, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Henrik Lindqvist, CFA. (2026, November 15). US Exorbitant Privilege & NIIP Valuation Effects Across Dollar Cycles. FXMacro Wire. https://fxmacrowire.com/wire/us-exorbitant-privilege-niip-valuation-dollar-cyclesRelated Safe Haven Capital Flow Regimes & Institutional Briefings
Explore Safe Haven Capital Flow Regimes Hub (20) →Safe Haven Capital Flow Regimes
G10 Safe-Haven FX Beta, NIIP & Balance-of-Payments Capital Flow Guide (2026)Safe Haven Capital Flow Regimes
Energy Supply Shocks & the Safe-Haven Flip: Why JPY & EUR Broke in StagflationSafe Haven Capital Flow Regimes
UK Twin Deficits & 31.4% Foreign Gilt Share: Modeling Sterling’s Risk BetaSafe Haven Capital Flow Regimes
CFTC TFF FX Positioning: Leveraged Funds vs Asset Managers & Pain TradesSafe Haven Capital Flow Regimes
Global M2 Liquidity Impulse & Central Bank Reserves: High-Beta AUD, NZD & SEKSafe Haven Capital Flow Regimes
Cross-Border M&A Deal-Contingent FX Forwards: Pricing Regulatory Tail RiskSafe Haven Capital Flow Regimes
Solvency II 25% FX Capital Charge: Why European Insurers Hedge 95% of USDSafe Haven Capital Flow Regimes
FX 25-Delta Risk Reversals & Butterflies: Reading Safe-Haven Tail SkewDigital Currency
ECB warns legislative delays could postpone digital euro launchDigital Currencies
Piero Cipollone: Cash and the digital euro: two sides of the same coinMarket Insights
Yuan Rally Likely to Cool, Not ReverseMarket Insights
Singapore Central Bank Rolls Out Gold-Vaulting Services
FXMacro Wire Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.