
Safe Haven Capital Flow Regimes
FX 25-Delta Risk Reversals & Butterflies: Reading Safe-Haven Tail Skew
Unlike equity options that list fixed strike prices on screens, institutional OTC foreign exchange options quote directly in volatility-smile space: At-The-Money Straddles, 25-Delta Risk Reversals, and 25-Delta Butterflies.
Walk onto an institutional G10 FX options desk in London, Zurich, or New York clearing part of FinDB's $9.60T Daily Global OTC FX Turnover, and ask for a price on a 1-month USD/JPY 145.00 put. Before quoting a single dollar premium, the market-maker's pricing engine builds the entire implied volatility smile from three interbank market-quoted building blocks:
- ATM (At-The-Money Delta-Neutral Straddle Volatility, sigma_ATM): Overall expected magnitude of movement.
- 25-Delta Risk Reversal (RR25D = sigma25DCall - sigma25D_Put): Directional Skew—which tail (upside or downside) the market fears most!
- *25-Delta Vega-Weighted Butterfly (BF_25D = 0.5 (sigma25DCall + sigma25DPut) - sigma_ATM): Smile Curvature /Kurtosis ("Fat Tails")**—the market's priced probability of discontinuous jumps or central bank peg breaks!
Why do spot macro traders who never trade options watch 1-month 25-Delta Risk Reversals in USD/JPY, EUR/USD, and EUR/CHF every morning at 07:00 London? Because institutional tail-hedgers and central-bank rate-check rumors move 25-Delta Risk Reversals 24 to 72 hours BEFORE spot breaks key technical support!
Exact Malz / Vanna-Volga Volatility Smile Reconstruction!#
Regulated OTC derivatives desks (ECB, FINMA, BaFin, IOSCO, executing across Blocksize Capital, Bequant, and CMC Central) invert the three screen quotes (ATM, RR25D, BF25D) to recover exact individual 25-Delta Call Volatility and 25-Delta Put Volatility in two lines of mental algebra!
Safe-Haven Skew Signatures Across Major Currency Pairs#
Be extremely careful with quoting convention (is the Risk Reversal quoted as "USD Call minus USD Put" or "Base Currency Call minus Put"? Standard interbank convention quotes Base Currency Call minus Base Currency Put: so in USD/JPY, a negative -2.20v Risk Reversal means USD Puts / JPY Calls trade 2.20 vols MORE expensive than USD Calls / JPY Puts!):
| Currency Pair (Base/Quote) | Calm-Regime 1M 25D RR | Crisis Panic 1M 25D RR | High Butterfly (>0.50v) Meaning | Actionable Spot Divergence Tell |
|---|---|---|---|---|
| USD/JPY (USD Base) | -1.10v to -1.90v | -3.20v to -5.50v (JPY Call panic!) | Upcoming BoJ/FOMC jump or MoF intervention fear! | Spot grinds to 158 while 1M RR drops -1.2v -> -2.8v = Imminent Drop! |
| EUR/CHF (EUR Base) | -0.75v to -1.35v | -2.40v to -4.10v (CHF Call bid!) | French/Italian election or SNB policy jump risk | 1M RR < -2.0v warns of European deposit flight (TARGET2 check) |
| EUR/USD (EUR Base) | -0.35v to +0.25v (Two-way!) | -1.60v to -2.50v (USD Smile bid!) | ECB/Fed meeting or tariff binary event | Rarely 1-way; RR flipping positive (+0.6v) confirms Dollar Smile Trough! |
| AUD/JPY (AUD Base) | -1.80v to -2.60v | -4.80v to -7.50v (Crash skew!) | Carry liquidation fat-tail kurtosis | Normalize RR / ATM (Skew Ratio) to compare across vol regimes! |
Exact Wing-Volatility Inversion & Normalized "Skew-to-ATM Ratio" Formula!#
Why should systematic FX models divide RR25D by sigmaATM (Normalized Skew Ratio = RR25D / sigmaATM) instead of reading raw vol points? Because -2.0 vols of Risk Reversal on 6.0% ATM vol (-33.3% normalized skew!) represents twice as extreme directional asymmetry as -2.0 vols on 12.0% ATM vol (-16.7% skew)!
- sigma25DPut = sigmaATM + BF25D - 0.5 * RR_25D
- NormalizedSkew = RR25D / sigma_ATM
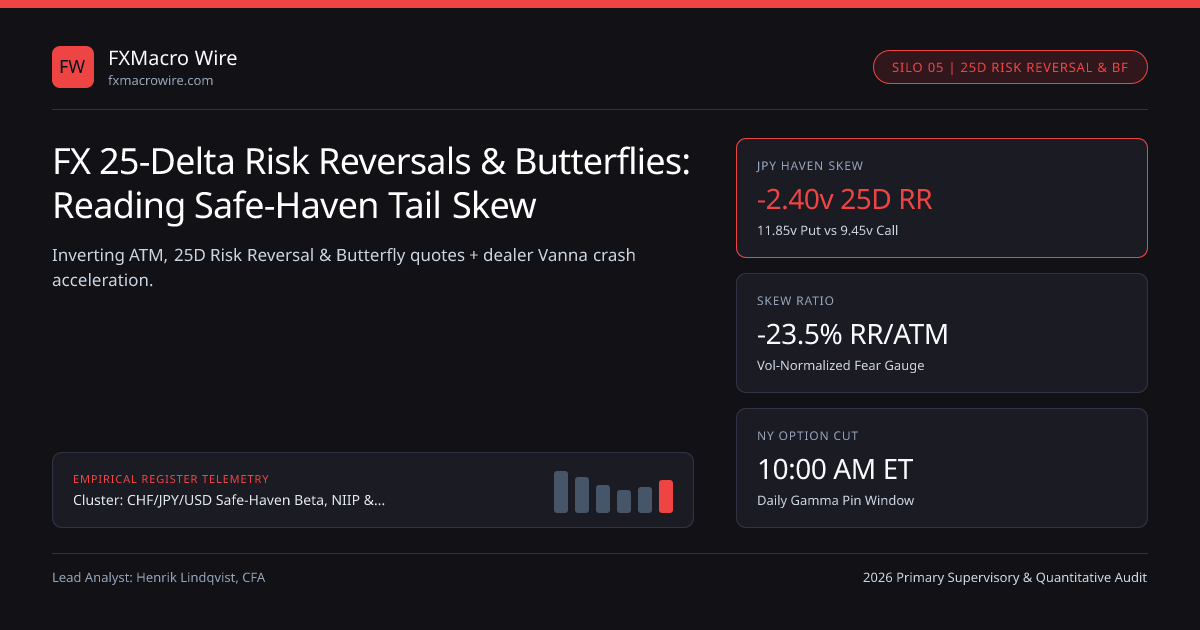
- Worked 1-Month USD/JPY Options Desk Quote Inversion (ATM = 10.20v, 25D RR = -2.40v, 25D BF = +0.45v):
- 1. 25-Delta USD Call / JPY Put Implied Vol = 10.20 + 0.45 + 0.5*(-2.40) = 10.65 - 1.20 = 9.45% vol
- 2. 25-Delta USD Put / JPY Call Implied Vol = 10.20 + 0.45 - 0.5*(-2.40) = 10.65 + 1.20 = 11.85% vol!
- 3. Normalized Skew Ratio = -2.40 / 10.20 = -0.235 (-23.5% premium for downside JPY safe-haven calls!)
Dealer "Vanna" Feedback Loops: Why Steep Negative Skew Accelerates Spot Crashes!#
Understand the second-order Greek Vanna (d(Delta) / d(Vol) = d(Vega) / d(Spot))—the secret mechanical accelerator behind violent safe-haven FX cascades:
- Market-making banks are structurally short 25-delta and 10-delta USD/JPY puts (sold to macro funds hedging carry crashes) and long 25-delta USD/JPY calls (sold by Japanese exporters overwriting upside).
- The instant spot USD/JPY drops -200 pips AND sigma_ATM jumps from 9.5v to 13.5v, rising implied volatility inflates the negative delta of those out-of-the-money puts (Vanna effect!)—forcing short-vanna option dealers to sell billions of spot USD/JPY into a falling market just to stay delta-neutral!
Integrating Volatility Surface Signals Across Silo 5#
Pair daily Normalized 25-Delta Skew (RR_25D / ATM) and 25-Delta Butterfly readings with our safe-haven FX & BoP hub guide, Dollar Smile regime turns, and CFTC TFF options-inclusive positioning—never pressing a crowded spot trend when the 1-month Risk Reversal diverges sharply against spot across our safe-haven FX & capital-flow regimes hub!
Frequently asked questions
What does it mean when EUR/USD 1-month 25-Delta Risk Reversals flip from negative to positive?
Historically EUR/USD Risk Reversals sit negative (-0.4v to -1.5v) because USD acts as the crisis funding haven; a flip above +0.40v signals options traders fear an upside EUR/USD breakout more than a downside dollar squeeze.
What causes a 25-Delta Butterfly (BF) to spike while the Risk Reversal stays near zero?
A high Butterfly with near-zero Risk Reversal signals symmetric bimodal jump risk—classic ahead of a binary referendum, tight central bank decision, or two-way peg/band test where spot could gap violently in EITHER direction.
What time of day do institutional OTC FX options expire?
Standard New York Cut FX options expire precisely at 10:00:00 AM Eastern Time (15:00 London typically), while Tokyo Cut Asian pairs expire at 15:00:00 JST—creating strong intraday spot "gamma pinning" around large strikes.
How do macro funds structure zero-cost FX tail hedges using skewed Risk Reversals?
When EUR/USD spot rallies into resistance while 3M EUR calls briefly trade richer than puts, hedgers sell rich upside calls to finance cheap downside EUR puts ("zero-cost collar / risk reversal").
Publication record
- Published
- 13 November 2026
- Updated
- 15 November 2026
- Author
- Henrik Lindqvist, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Henrik Lindqvist, CFA. (2026, November 15). FX 25-Delta Risk Reversals & Butterflies: Reading Safe-Haven Tail Skew. FXMacro Wire. https://fxmacrowire.com/wire/fx-25-delta-risk-reversal-butterfly-safe-haven-skewRelated Safe Haven Capital Flow Regimes & Institutional Briefings
Explore Safe Haven Capital Flow Regimes Hub (20) →Safe Haven Capital Flow Regimes
G10 Safe-Haven FX Beta, NIIP & Balance-of-Payments Capital Flow Guide (2026)Safe Haven Capital Flow Regimes
Sovereign Wealth Fund & Petrodollar Recycling: ADIA, PIF, QIA & NBIM FX FlowsSafe Haven Capital Flow Regimes
Post-NIRP Eurozone Bond Repatriation: Positive Bund Yields & Structural EUR SupportSafe Haven Capital Flow Regimes
US Fiscal Deficits, Term Premium & Private FX-Hedged UST Demand: Dollar EndgameSafe Haven Capital Flow Regimes
NIIP Creditor Repatriation (CHF & JPY) vs USD Debtor Safe-Haven MechanicsSafe Haven Capital Flow Regimes
The Dollar Smile Framework: US Exceptionalism vs Global Funding StressSafe Haven Capital Flow Regimes
US Treasury TIC Form SLT Flows: FX-Hedged vs Unhedged UST & Equity DemandSafe Haven Capital Flow Regimes
Broad Basic Balance (BBoP): Current Account + Net FDI as a G10 FX AnchorRegulatory Compliance
Nigeria sets new crypto licensing rules, bans algorithmic stablecoinsForeign Exchange
China Forex Reserves Edged Up in OctoberMonetary Policy
Waller, The Signaling Value of the Summary of Economic ProjectionsMarket Insights
ECB publishes consolidated banking data for end-June 2026
FXMacro Wire Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.