
Safe Haven Capital Flow Regimes
US Fiscal Deficits, Term Premium & Private FX-Hedged UST Demand: Dollar Endgame
Running -6% of GDP peace-time full-employment federal budget deficits forces the US Treasury to auction ~$2.0 trillion of net duration annually—shifting marginal US bond pricing from price-insensitive central banks to FX-hedged and repo-funded private investors.
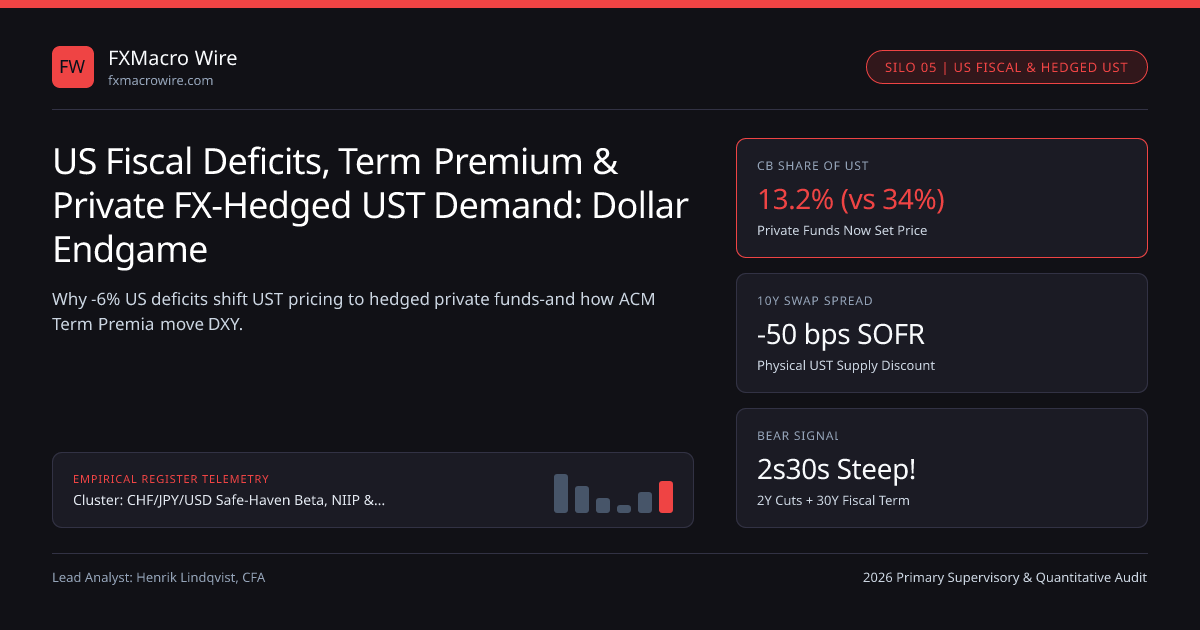
Here is the ultimate macro endgame question debated across every central bank reserve board and multi-billion-dollar sovereign macro committee in 2026: if the United States runs persistent -5.8% to -6.5% of GDP federal budget deficits at full employment (requiring ~$2.0T/year in net marketable US Treasury issuance as federal debt held by the public crosses 100%+ of GDP), is massive US fiscal borrowing BULLISH for ICE US Dollar Index (DXY) (via higher real yields) OR BEARISH for DXY (via Twin-Deficit / Fiscal Term-Premium erosion)?
Institutional FX and rates strategists audited across ECB, BCBS / BIS, and global financial stability forums (trading across Blocksize Capital, Bequant, and CMC Central) resolve this debate by tracking WHO buys the marginal $2.0 trillion of US Treasuries—and how 10-year US Term Premium (ACM Term Premium) interacts with 2-year OIS spreads!
Shift in Marginal UST Ownership: From Price-Insensitive Central Banks (2004–14) to Price-Sensitive Private Buyers (2022–26)!#
Look at the historic buyer rotation inside the $28.5+ trillion marketable US Treasury market:
- 2004–2014 Era (Central Bank Reserve Monopoly): Foreign central banks (IMF COFER pool: China SAFE, Japan MoF) + the Federal Reserve owned >55% of marketable USTs—buying price-insensitively with 0% FX hedging!
- 2022–2026 Era (Private Price-Elastic Buyer Dominance!): Official foreign central bank UST holdings plateaued near ~$3.8T (falling from 34% down to ~13% of total UST debt!) while the Fed shrank SOMA via QT! Who bought the extra $10+ trillion of US debt? Domestic US money-market/households (~68%) + Foreign PRIVATE Investors (~$5.0T: Cayman repo-basis hedge funds + European/Asian insurers & pensions)!
- Crucial FX Link (TIC SLT Hedge Proof): Because foreign private buyers either fund in USD repo (Cayman basis) OR FX-hedge 70%–95% of currency risk (Solvency II insurers, 25% FX SCR rule), $500B of foreign private UST buying generates almost ZERO net spot USD appreciation—unless US equities keep outperforming simultaneously!
The Four Diagnostic Indicators That Separate "Bullish Fiscal Stimulus" From "Bearish Fiscal Supply Indigestion"!#
How do you know in real time on your Bloomberg / FinDB terminal whether rising 10-year US Treasury yields are Phase 1 Bullish USD (strong growth) or Phase 2 Bearish USD (bond supply indigestion)? Check all four market gauges below—the exact developed-market twin of our UK Gilt-GBP correlation switch:
| US Rates & Cross-Asset Gauge | Phase 1: Bullish US Exceptionalism (2022–24) | Phase 2: Bearish Supply Indigestion (Endgame) | Spot DXY & EUR/USD Implication |
|---|---|---|---|
| US Yield Curve (2s30s) | Bear Flattener / Inverted (2Y leads up!) | Bear Steepener! (Fed cuts 2Y while 30Y stays >4.7%!) | Bearish DXY: FX carry tracks 2Y OIS, NOT 30Y supply! |
| 10Y UST SOFR Swap Spread | Stable (-20 to -30 bps) | Collapses deeper (-50 to -65 bps!) | Cash Treasuries cheapen vs derivatives on sheer bond glut |
| NY Fed 10Y ACM Term Premium | Negative to +15 bps (Growth/Fed driven) | Surges > +75 to +120 bps (Pure duration risk tax) | Higher 10Y yield reflects supply penalty, not real growth! |
| S&P 500 vs MSCI EAFE + Gold | US Mega-Cap Tech crushes EAFE & Gold | Gold surges >$2,700+ & EAFE catches up to S&P! | Foreign unhedged equity USD inflows stall -> Buy EUR/USD & CHF! |
Quantitative Decomposition: 2-Year OIS Carry vs 10-Year ACM Term-Premium Divergence!#
Empirical G10 FX regressions across forty years (1985 Reagan Twin Deficits, 2002–2007 Bush Twin Deficits, and 2021–2026) confirm a razor-sharp asymmetric beta on DXY (DXY 2026 Standard): +50 bps in Expected Fed Policy Path (2Y OIS) rallies DXY by ~+2.8%, whereas +50 bps in pure Fiscal Supply Term Premium (with 2Y OIS flat or falling!) WEAKENS DXY by -1.4% to -2.2%!
- Delta ln(DXYt) = +5.6 * Delta( Et[SOFR2Y] - ForeignOIS2Y ) - 3.2 * Delta( USFiscalTermPremiumt ) + 0.45 * UnhedgedUSEquityFlow
- Worked Phase-2 "Bear Steepener" Dollar Bear Scenario:
- Suppose US labor market cools -> Fed cuts rates -> 2Y SOFR-ESTR spread narrows by -75 bps (-0.75%),
- WHILE $2.1T Treasury issuance lifts 10Y NY Fed ACM Term Premium by +45 bps (+0.45%) [10Y UST barely falls!]:
- 2Y Policy Expectations Channel = +5.6 * (-0.75%) = -4.20% DXY drag
- 10Y Fiscal Term Premium Penalty = -3.2 * (+0.45%) = -1.44% DXY drag
- > Combined Spot DXY Move = -5.64% DROP even though headline 10Y US Treasury yield stayed near 4.40%!!
The Self-Stabilizing Valve: Why Curve Steepening Eventually Re-Attracts FX-Hedged Foreign Buyers!#
Notice why a Phase-2 US dollar decline is an orderly cyclical -10% to -15% repricing (like 2003–2006), NOT an apocalyptic reserve-currency collapse:
- Once Fed 2-year cuts + rising 10-year ACM Term Premium re-steepen the US 10s3M Treasury curve to +100–150 bps positive slope, FX-hedged 10-year US Treasuries suddenly pay €STR + 120 bps to European insurers and TONA + 135 bps to Japanese lifers!
- Trillions of global pension and insurance savings rush back in to lock in steep FX-hedged US duration—stabilizing 10Y Treasury yields while a -12% softer DXY painlessly boosts America's NIIP by +$3.0 trillion via Gourinchas-Rey valuation gains (Exorbitant Privilege valuation stabilizer)!
Concluding Silo 5 & Full Institutional FX Mastery#
From positive-NIIP creditor repatriation in Zurich and Tokyo to Stephen Jen's Dollar Smile, TIC hedge decompositions, WMR month-end fixings, Solvency II capital charges, and America's fiscal endgame, synthesize all twenty guides across our safe-haven FX & BoP hub guide and safe-haven FX & capital-flow regimes hub!
Frequently asked questions
What is the NY Fed ACM Term Premium and why do FX strategists watch it?
Developed by Adrian, Crump, and Moench at the New York Fed, the ACM model splits the 10-year Treasury yield into expected future short-term Fed rates versus the extra compensation ("Term Premium") investors demand for holding long-duration supply/inflation risk.
Why did 10-year US Treasury SOFR swap spreads fall deeply negative (-45 to -55 bps)?
Negative swap spreads mean cash 10-year US Treasuries yield 45-55 bps MORE than 10-year risk-free SOFR OIS swaps—reflecting heavy physical Treasury bond supply clogging primary-dealer balance sheets under SLR leverage constraints.
Why does a 2s30s US Treasury "Bear Steepener" weaken the US dollar?
FX forward carry is anchored to 3-month and 2-year interest-rate differentials; if 2-year US yields fall on Fed cuts while 30-year yields rise on fiscal deficit fears, the dollar loses its carry advantage AND suffers a fiscal risk discount simultaneously.
Could US Bank Supplementary Leverage Ratio (SLR) reform help stabilize Treasury swap spreads and USD?
Exempting cash US Treasuries or central bank reserves from G-SIB Supplementary Leverage Ratio denominators expands primary-dealer balance-sheet capacity to warehouse Treasury auctions without demanding steep swap-spread concessions.
Publication record
- Published
- 13 November 2026
- Updated
- 14 November 2026
- Author
- Henrik Lindqvist, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Henrik Lindqvist, CFA. (2026, November 14). US Fiscal Deficits, Term Premium & Private FX-Hedged UST Demand: Dollar Endgame. FXMacro Wire. https://fxmacrowire.com/wire/us-fiscal-deficit-private-hedged-ust-demand-dollarRelated Safe Haven Capital Flow Regimes & Institutional Briefings
Explore Safe Haven Capital Flow Regimes Hub (20) →Safe Haven Capital Flow Regimes
G10 Safe-Haven FX Beta, NIIP & Balance-of-Payments Capital Flow Guide (2026)Safe Haven Capital Flow Regimes
NIIP Creditor Repatriation (CHF & JPY) vs USD Debtor Safe-Haven MechanicsSafe Haven Capital Flow Regimes
The Dollar Smile Framework: US Exceptionalism vs Global Funding StressSafe Haven Capital Flow Regimes
US Treasury TIC Form SLT Flows: FX-Hedged vs Unhedged UST & Equity DemandSafe Haven Capital Flow Regimes
Broad Basic Balance (BBoP): Current Account + Net FDI as a G10 FX AnchorSafe Haven Capital Flow Regimes
Swiss Franc Real Safe-Haven Math: +9.5% Pharma Surplus, CPI Gap & EUR/CHFSafe Haven Capital Flow Regimes
Japan’s Structural Yen Drag: Digital Deficit, Energy Bill & Unrepatriated FDISafe Haven Capital Flow Regimes
Month-End WMR 16:00 London Fix: Equity-FX Hedge Rebalancing SignalsMarket Insights
ECB publishes consolidated banking data for end-June 2026Regulatory Benchmarks
G10 Foreign Exchange & European MiFID Brokerage 2026 Licensing Benchmark: 6D Prudential Scorecard Across 57 Audited EntitiesCompliance Forensics
How to Verify G10 Foreign Exchange & European MiFID Brokerage Licences & Detect Clone Firms: 2026 Supervisory Lookup PlaybookSolvency and Protection
Investor Compensation Ceilings, Client-Money Segregation & Counterparty Risk Matrix in G10 Foreign Exchange & European MiFID Brokerage (2026)
FXMacro Wire Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.