
Scandinavian STIBOR & NIBOR Year-End FX Swap USD Squeezes (SEK & NOK)
Every December, Swedish krona (USD/SEK) and Norwegian krone (USD/NOK) FX swaps experience the most violent year-end turn kinks in G10 markets as Swedish bank resolution-fee snapshots collide with massive Nordic pension hedge rolls.
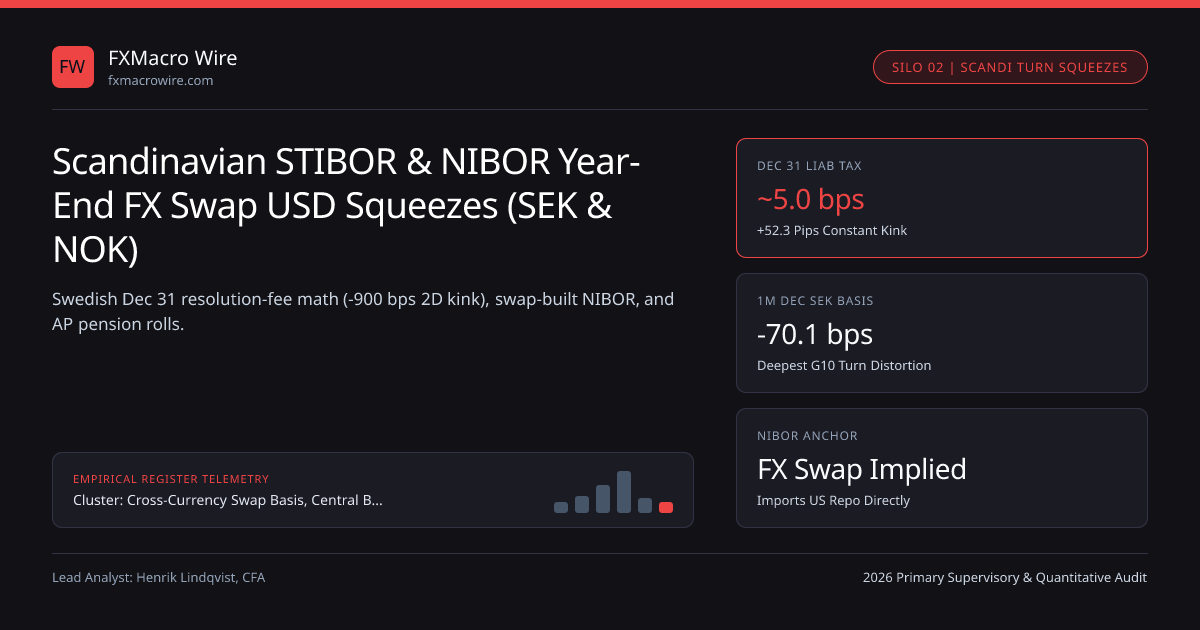
Nowhere in the G10 currency universe do year-end balance-sheet distortions hit harder than in Stockholm (USD/SEK) and Oslo (USD/NOK)—benchmark pillars of FinDB's NOK/SEK Scandi Policy Divergence Index and 2026 Scandi Standard. Every late December, implied overnight Swedish krona rates embedded inside USD/SEK FX swaps routinely plunge -150 to -450 basis points below Riksbank policy rates (equivalent to a massive -60 to -95 bps 1-month cross-currency basis!), driven by a toxic collision between Sweden's point-in-time December 31st Bank Resolution Fee and $450 billion+ in Swedish AP/occupational pension USD equity hedges!
Sweden's December 31st Resolution Fee Snapshot: Why SEK Implied Rates Go Deeply Negative!#
Under the Swedish National Debt Office (Riksgälden) and Finansinspektionen (FI Sweden) implementation of the EU Bank Recovery and Resolution Directive, Swedish commercial banks (SEB, Handelsbanken, Swedbank—alongside regional players like Abonea AB and Nordic-Baltic peers supervised by FIN-FSA Finland and DFSA Denmark) pay an annual Resolution Reserve Fee (~5 bps of total non-equity liabilities) calculated strictly on their SINGLE point-in-time December 31st balance sheet!
Think through the brutal one-day arithmetic: paying a 5.0 basis point annual tax on total liabilities held for just ONE calendar night (December 31st) equals an annualized balance-sheet penalty of 5.0 bps × 360 = 1,800 basis points (18.0%/yr!) for expanding a Swedish bank's balance sheet across New Year's Eve! Consequently, Swedish banks refuse to accept wholesale SEK deposits or intermediate matched-book USD/SEK swaps over December 31st unless compensated by extraordinary forward-point concessions!
Norway's Contrasting Mechanism: NIBOR Structural Liquidity & Petroleum Tax Drains#
Across the border in Oslo, USD/NOK FX swaps play a central role in Norwegian domestic money markets: Norway's benchmark NIBOR (Norwegian Interbank Offered Rate) is literally constructed from USD funding plus USD/NOK FX swap points because Norway lacks a deep unsecured interbank deposit market!
Comparing Scandi money-market plumbing with our cross-currency swap basis hub, EUR/USD G-SIB turn window-dressing, and US TGA fiscal reserve drains highlights why NOK swap rates spike in the opposite direction around Norwegian petroleum tax installments (6 annual installments) when oil companies transfer tens of billions of kroner to Norges Bank's government account—draining structural bank reserves unless offset by Norges Bank F-loans! Notice also that neither Riksbank nor Norges Bank belongs to the permanent C7 standing Fed swap network, relying instead on FX reserves and NY Fed FIMA repo!
| Nordic FX Swap Corridor | Primary Benchmark Rate | Dominant Year-End Distortion | Typical 1M Dec Basis | Central Bank Smoothing Tool |
|---|---|---|---|---|
USD/SEK (STIBOR / SWESTR) | SWESTR RFR / 3M STIBOR | FI Sweden / Riksgälden Dec 31 resolution fee + AP pensions | -55 to -85 bps | Riksbank Debt Office T-Bill repos |
USD/NOK (NOWA / NIBOR) | FX-swap-derived NIBOR | Thin year-end Norges Bank structural quota + foreign bank cap | -40 to -65 bps | Norges Bank F-loans & F-deposits |
EUR/DKK (DESTR / CIBOR) | ERM II 7.46038 peg | DFSA Denmark / Danish pension ATP/PFA EUR hedges | -18 to -28 bps vs EUR | Danmarks Nationalbank CDs |
| NOK/SEK Cross Swap | Synthetic USD/NOK vs USD/SEK | Relative SEK Dec 31 tax vs NOK structural cash tightness | +20 to +35 bps SEK rich | Pure RV cross-turn calendar spread |
Quantitative Math of the Swedish 1-Day Resolution-Fee FX Swap Kink#
Let's verify how a seemingly tiny 5.0 bps (0.05%) annual bank resolution fee assessed on a single snapshot night (Dec 31 -> Jan 2, d_{turn} = 2 weekend/holiday days) distorts a 31-day December USD/SEK FX swap (N = 31):
- Impacton1MBasis = - Fee{annual_liab} * ( 360 / N )
- ExtraSEKForwardOre = Spot{USDSEK} * Fee{annualliab}
- Worked December 1-Month (N = 31 Days, d_{turn} = 2 Days) USD/SEK Swap Distortion (Spot = 10.4500 SEK):
- Swedish Bank Resolution + Systemic Liability Fee on Dec 31 balance sheet = 5.0 bps (0.0005 flat charge)
- Implied 2-Day Turn Hurdle = 5.0 bps * (360 / 2) = 900.0 bps/year (-9.00% annualized implied SEK rate drop!)
- Contribution to 31-Day 1M USD/SEK XCCY Basis = -5.0 bps * (360 / 31) = -58.06 bps added to clean -12 bps = -70.1 bps!
- Exact Forward Point Jump Regardless of Tenor = 10.4500 * 0.0005 = +0.005225 SEK (+52.3 pips / 0.52 öre instant jump!)
(Notice that elegant constant-pip law: a flat 5.0 bps snapshot tax adds +52.3 pips (Spot × 0.0005)* to EVERY USD/SEK forward maturity the instant it crosses December 31st—whether 3M in September, 1M in November, or Tom/Next on December 30th!)*

Relative-Value Trading & Pension Roll Defense in Scandi Swaps#
Swedish occupational pension giants (Alecta, AMF, Skandia, and AP1-AP4 buffer funds) learned the hard way never to leave 100% of their $320B+ USD equity hedges rolling inside December! By pre-rolling USD/SEK forwards in October/November across February/March maturities, Nordic pensions sidestep peak dealer lockups.
Cross-Scandi NOK/SEK Forward Turn Arbitrage#
Because Sweden's December 31st bank resolution tax hits SEK liabilities harder than Norway's structural quota squeezes hit NOK, macro relative-value desks routinely receive December NOK/SEK forward points in mid-November and unwind on January 2nd—harvesting 20 to 35 bps of clean Nordic regulatory dispersion across our FX swap basis & dollar funding hub.
Frequently asked questions
Why do implied Swedish krona interest rates turn deeply negative over New Year’s Eve?
Swedish banks pay an annual ~5 bps resolution reserve fee based solely on their December 31st liability snapshot; avoiding SEK deposits for that single night equals a 900-1,800 bps annualized cost passed directly into USD/SEK FX swaps.
How is Norwegian NIBOR uniquely tied to the US dollar FX swap market?
Because unsecured interbank term lending in kroner is thin, NIBOR panel banks calculate quotes by taking wholesale USD borrowing costs and swapping them into NOK via USD/NOK FX swaps—importing US TGA and quarter-end repo swings into Norway!
Do Sveriges Riksbank and Norges Bank have standing Federal Reserve USD swap lines?
No. Unlike the C7 peers (ECB, BoJ, BoE, SNB, BoC), Riksbank and Norges Bank only received temporary $30B-$60B Fed swap lines during 2008 and 2020 crises, relying normally on FX reserves and NY Fed FIMA Repo.
How do Swedish AP pension funds avoid paying punitive December USD/SEK roll spreads?
Swedish pension overlays execute 6-month and broken-date forward rolls in August-October spanning into Q1, avoiding maturity renewals during December bank balance-sheet lockups.
Publication record
- Published
- 14 November 2026
- Updated
- 14 November 2026
- Author
- Henrik Lindqvist, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Henrik Lindqvist, CFA. (2026, November 14). Scandinavian STIBOR & NIBOR Year-End FX Swap USD Squeezes (SEK & NOK). FXMacro Wire. https://fxmacrowire.com/wire/scandi-stibor-nibor-year-end-fx-swap-usd-squeezesRelated FX Swap Basis Dollar Funding & Institutional Briefings
Explore FX Swap Basis Dollar Funding Hub (20) →FX Swap Basis Dollar Funding
Cross-Currency Swap Basis, Fed Swap Lines & Global Dollar Funding Guide (2026)FX Swap Basis Dollar Funding
USD/SGD SORA-SOFR FX Swap Points & Asian Dollar Funding MechanicsFX Swap Basis Dollar Funding
EUR/USD 3-Month XCCY Basis & G-SIB Year-End Balance-Sheet Window DressingFX Swap Basis Dollar Funding
5-Year G10 Cross-Currency Basis & Corporate Yankee vs Reverse-Yankee ArbitrageFX Swap Basis Dollar Funding
Federal Reserve C7 Standing Dollar Swap Lines: OIS + 25 bps Ceiling MechanicsFX Swap Basis Dollar Funding
BIS Offshore Dollar FX Swap Debt & Non-Bank Rollover Stress MechanicsFX Swap Basis Dollar Funding
USD/JPY TONA-SOFR XCCY Basis & Japanese Megabank Dollar FundingFX Swap Basis Dollar Funding
Covered Interest Parity Deviations & Basel III Leverage Ratio Shadow CostsSovereign FX Reserves Intervention
G7 Coordinated FX Intervention vs Unilateral Strikes & NY Fed Rate ChecksEm Carry Terms of Trade Shocks
USD/BRL & USD/MXN Carry-to-Vol Ratios: Selic vs Banxico Real Yield MathEm Carry Terms of Trade Shocks
BIS Broad vs Narrow REER Indices: CPI vs ULC Currency MisalignmentsEm Carry Terms of Trade Shocks
Copper Terms-of-Trade Shocks: CLP, PEN & AUD/USD Exchange-Rate Betas
FXMacro Wire Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.