
US Treasury TGA Rebuilds, ON RRP Exhaustion & Offshore FX Swap Basis Spikes
Once the Federal Reserve’s Overnight Reverse Repo (ON RRP) buffer drained near floor levels, every $200 billion US Treasury General Account (TGA) tax-date or debt-ceiling rebuild began pulling dollar reserves directly out of G-SIB FX swap desks.
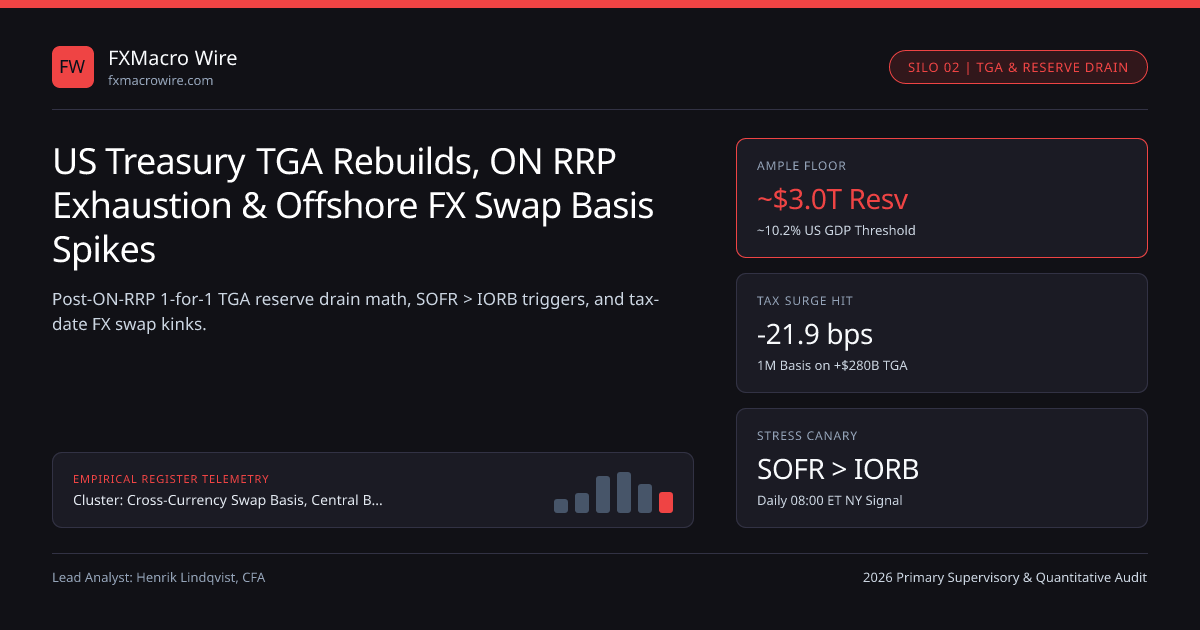
Between 2022 and early 2024, over $2.2 trillion parked inside the New York Fed's Overnight Reverse Repo (ON RRP) facility acted as a giant shock absorber for global dollar markets: whenever the US Treasury issued T-Bills to rebuild its Treasury General Account (TGA), US money-market funds simply rotated cash out of ON RRP into T-Bills without draining commercial bank reserves! In 2025-2026, with ON RRP buffers largely exhausted, every $100 billion rise in TGA (around April 15 tax deadlines, corporate quarterly tax dates, or post-debt-ceiling T-Bill floods) drains $100 billion 1-for-1 out of Federal Reserve bank reserves, spiking onshore SOFR repo and immediately widening offshore EUR/USD and USD/JPY FX swap basis!
The Federal Reserve Autonomous Liability Identity Driving Global Dollar Plumbing#
Every macro FX desk tracks the fundamental weekly Federal Reserve H.4.1 accounting identity linking Fed assets (SOMA + Loans) against autonomous non-reserve liabilities (Currency + TGA + ON RRP + Foreign Repo Pool):
When ON RRP ≈ $0-$100B and Fed assets are flat or shrinking, any surge in the US Treasury's checking account (+Delta TGA) mechanically subtracts an identical dollar amount from US commercial bank reserves (-Delta Reserves)! Because US and foreign G-SIB New York branches must preserve internal Lowest Comfortable Level of Reserves (LCLoR) under Regulation YY intraday liquidity stress tests, the first balance-sheet activity they curtail when reserves approach ~$2.9-$3.1 trillion (~10%-11% of US GDP) is discretionary matched-book repo and offshore Tom/Next FX swap lending!
As integrated into our cross-currency swap basis hub, G-SIB turn window-dressing models, and Fed C7 standing swap line ceilings, onshore NY repo pressure transmits into London and Tokyo FX swap points within 15 minutes of the 08:00 ET US repo open!
Calendar Map of Predictable TGA & Treasury Settlement Squeezes#
European and global liquidity managers supervised by ECB, BaFin, FINMA, and CSSF—executing overnight cash and FX swaps through institutional desks alongside Blocksize Capital and Bequant—overlay two recurring US fiscal calendars onto FX swap roll dates:
- Quarterly Corporate & Individual Tax Deadlines: April 15, June 15, September 15, and December 15, when corporate tax wires pull $150B-$350B out of corporate bank deposits into the TGA at the Fed within 72 hours.
- Mid-Month & Month-End US Treasury Coupon Settlement Dates: 15th and last business day of every month, when primary dealers must finance $60B-$120B of net new 2Y/5Y/10Y/30Y Treasury settlements in overnight repo—remembering the September 16-17, 2019 "Repo-calypse" when corporate tax inflows + coupon settlements spiked overnight US repo to 10% and blew out 1-week EUR/USD and USD/JPY FX swaps!
| Liquidity Plumbing Regime | NY Fed ON RRP Balance | US Bank Reserves (% GDP) | SOFR minus IORB Spread | 1W-1M FX Swap Basis Behavior |
|---|---|---|---|---|
| Abundant Reserves (2022-2023) | $1.5T - $2.5T cushion | 12.5% - 14.0% GDP | -7 to -5 bps (soft floor) | Immune to TGA T-Bill issuance |
| Upper-Ample Transition (2026) | $50B - $200B residual | 10.2% - 11.2% GDP | -2 to +6 bps (settlement kinks) | -4.2 bps 1M FX basis per +$100B TGA |
| Borderline Scarce Stress (Sep 2019) | $0B exhausted | < 8.5% GDP (LCLoR hit) | +15 to +300 bps spikes! | Violent -35 to -80 bps 1W FX blowouts |
| SRF + C7 Capped Equilibrium | Domestic SRF active | ~10.0% GDP floor | Capped at SRF (+10-15bp > IORB) | Capped by SRF & C7 Swap Lines |
Quantitative Reserve-Accounting & FX Swap Basis Elasticity Model#
Let's formalize the weekly Federal Reserve reserve-supply change (Delta R_t) and its nonlinear transmission into 1-month G10 cross-currency basis (Delta b_{1M}) once ON RRP drops below its frictional floor:
- Spread{SOFR-IORB,t} = alpha0 + gamma * max( 0 , R{amplethreshold} - Reserves_t )
- Delta b{1M,EURUSD} = -1.35 * Delta Spread{SOFR-IORB,t} - 0.042 * ( Delta TGA_{$B} / 100 )
- Worked Mid-April US Tax + Coupon Settlement Week Stress Simulation (ON RRP Fixed at $80B Floor):
- Treasury TGA jumps +$280B ($520B -> $800B); SOMA flat ($0B); Reserves drop $3.18T -> $2.90T ($100B below $3.00T threshold)
- SOFR-IORB spread jumps +7.5 bps (gamma = 7.5 bps per $100B below threshold)
- Predicted 1M EUR/USD XCCY Basis Widening = -1.35(7.5) - 0.042(280/100)*100? Wait: -4.2 bps per $100B!
- Exact Basis Widening = -1.35(7.5 bps) - 4.2(2.8) = -10.13 - 11.76 = -21.9 bps (1M basis moves -14 -> -35.9 bps!)
How the Domestic Standing Repo Facility (SRF) Interacts with Offshore C7 Swaps#
Today, the New York Fed's domestic Standing Repo Facility (SRF) lets US primary dealers and eligible US banks borrow cash overnight against Treasuries at the top of the Fed Funds range—preventing a repeat of September 2019's 10% repo spike. However, SRF cash stays inside US primary-dealer balance sheets subject to G-SIB leverage caps!
Hedging Calendar Risk Around US Debt-Ceiling X-Dates#
Whenever Congress resolves a statutory debt-ceiling standoff—allowing the US Treasury to rebuild TGA from under $100B back to $850B via a $750B T-Bill wave over 8 weeks—institutional overlay managers lock in 3-to-6-month EUR/USD and USD/JPY swaps before debt-ceiling passage to front-run the 15-to-22 bps reserve-drain basis widening across our FX swap basis & dollar funding hub.
Frequently asked questions
What is the US Treasury General Account (TGA) and how does it affect FX swap rates?
The TGA is the US federal government’s operating checking account at the Federal Reserve; when tax receipts or T-Bill auctions swell the TGA, dollars leave commercial bank reserves, tightening NY bank liquidity and widening FX swap basis.
Why didn’t TGA rebuilds widen FX swap basis in 2023 when T-Bill supply exceeded $1 trillion?
In 2023, US money-market funds held over $2.2 trillion in the Fed’s Overnight Reverse Repo (ON RRP) facility and simply shifted cash from ON RRP into T-Bills, leaving commercial bank reserves completely unchanged.
What is the single best daily indicator of onshore US dollar reserve scarcity?
The spread between Secured Overnight Financing Rate (SOFR) and Interest on Reserve Balances (IORB): when SOFR consistently prints +3 to +10 bps above IORB outside quarter-ends, bank reserves are entering the scarce friction zone.
What happened during the September 2019 US repo spike in FX swap markets?
On September 16-17, 2019, simultaneous corporate tax inflows to the TGA and $54B of Treasury coupon settlements drained reserves below bank comfort floors, spiking US repo to 10% and blowing out 1-week EUR/USD and USD/JPY swap basis.
Publication record
- Published
- 14 November 2026
- Updated
- 14 November 2026
- Author
- Henrik Lindqvist, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Henrik Lindqvist, CFA. (2026, November 14). US Treasury TGA Rebuilds, ON RRP Exhaustion & Offshore FX Swap Basis Spikes. FXMacro Wire. https://fxmacrowire.com/wire/tga-rebuilds-on-rrp-drain-offshore-fx-swap-ratesRelated FX Swap Basis Dollar Funding & Institutional Briefings
Explore FX Swap Basis Dollar Funding Hub (20) →FX Swap Basis Dollar Funding
Cross-Currency Swap Basis, Fed Swap Lines & Global Dollar Funding Guide (2026)FX Swap Basis Dollar Funding
SA-CCR Counterparty Credit Capital Charges on Institutional FX Swap BooksFX Swap Basis Dollar Funding
UMR Phase 6 Initial Margin Rules: FX Forwards vs Cross-Currency SwapsFX Swap Basis Dollar Funding
SOFR-ESTR Mark-to-Market Resetting Cross-Currency Basis Swap ConventionsFX Swap Basis Dollar Funding
Scandinavian STIBOR & NIBOR Year-End FX Swap USD Squeezes (SEK & NOK)FX Swap Basis Dollar Funding
USD/SGD SORA-SOFR FX Swap Points & Asian Dollar Funding MechanicsFX Swap Basis Dollar Funding
EUR/USD 3-Month XCCY Basis & G-SIB Year-End Balance-Sheet Window DressingFX Swap Basis Dollar Funding
5-Year G10 Cross-Currency Basis & Corporate Yankee vs Reverse-Yankee ArbitrageSovereign FX Reserves Intervention
BIS Medium-Term Instruments (MTIs), Fixbis & Sovereign Reserve ConfidentialitySovereign FX Reserves Intervention
IMF Assessing Reserve Adequacy (ARA) Metric vs Guidotti-Greenspan RulesSovereign FX Reserves Intervention
Off-Balance-Sheet Central Bank FX Forwards, Swaps & IMF SDDS Reporting LagsSovereign FX Reserves Intervention
Norges Bank Daily NOK FX Conversions & $1.8T NBIM Petroleum Fiscal Rule
FXMacro Wire Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.