
Em Carry Terms of Trade Shocks
USD/BRL & USD/MXN Carry-to-Vol Ratios: Selic vs Banxico Real Yield Math
Latin America anchors global emerging-market foreign exchange carry through Brazil’s Selic and Mexico’s Banxico policy rates—yet contrasting CLS liquidity, NDF mechanics, and fiscal risk create sharply divergent carry-to-volatility profiles.
Within institutional emerging-market foreign exchange portfolios, Mexican peso (USD/MXN) and Brazilian real (USD/BRL) represent the twin liquidity pillars of high-carry Latin American macro allocation. Together accounting for over $210 billion in combined daily spot, swap, and NDF volume inside BIS $9.60T OTC FX Turnover, both central banks—Banco Central do Brasil (BCB) and Banco de México (Banxico)—historically maintain among the highest ex-ante real policy interest rates (5.50% to 7.50% real!) in the G20.
Yet treating MXN and BRL as interchangeable LatAm proxies is a classic portfolio error: MXN trades 24 hours a day as a fully deliverable, CLS-settled global risk proxy, whereas BRL trades offshore via cash-settled Non-Deliverable Forwards (PTAX fixing) and exhibits steeper domestic fiscal-dominance sensitivity!
Structural Microstructure Contrast: Deliverable 24-Hour MXN vs Offshore PTAX-Settled BRL#
Before comparing nominal yield spreads, institutional execution desks supervised under ECB, BaFin, and IOSCO standards (routing liquidity across venues such as Blocksize Capital, Bequant, and B2BX Exchange) separate how each currency clears:
- Mexican Peso (MXN): Fully convertible, free-floating, and CLS Bank PvP eligible since 2008. Spot USD/MXN trades continuously across Tokyo, London, and New York hours with 1–2 pip institutional spreads—making MXN the first currency macro hedge funds short at 02:00 London time as a liquid proxy hedge whenever global risk sentiment sours!
- Brazilian Real (BRL): Restricted onshore currency (Conta 4373 / Resolution 2,689 rules). Offshore macro funds trade USD/BRL Non-Deliverable Forwards (NDFs) settling in USD against BCB's daily 13:15 BRT composite PTAX fixing (an arithmetic average of four intraday 2-minute dealer query windows!), while true onshore price discovery concentrates in B3 WDO / DOL futures and BCB Swap Cambial (BCB Swap Cambial & Cupom Cambial liquidity) between 09:00 and 18:00 BRT.
Head-to-Head Institutional Comparison: USD/BRL vs USD/MXN#
Notice how economic drivers diverge sharply across commodity terms of trade, US manufacturing linkages, and fiscal sensitivity:
| Institutional Dimension | Brazilian Real (USD/BRL) | Mexican Peso (USD/MXN) | Portfolio Alpha Implication |
|---|---|---|---|
| Primary Settlement | Offshore USD NDF vs BCB PTAX; B3 futures | 24/5 Deliverable Spot & Forward (CLS PvP) | MXN gaps in Asian hours; BRL gaps at 09:00 BRT B3 open! |
| Ex-Ante Real Policy Rate | Selic minus BCB Focus 12M IPCA (~7.4% real) | Banxico TIIE minus 12M CPI (~5.4% real) | BRL pays +180 to +240 bps higher real coupon than MXN |
| External Balance Driver | Soybeans, iron ore, pre-salt crude oil (+$75B-$95B trade surplus!) | US industrial nearshoring + $63B/yr worker remittances | BRL tracks China/commodity cycle; MXN tracks US ISM & tariffs |
| Achilles Heel / Tail Risk | Primary fiscal deficit targets & public debt (~78% GDP) | Crowded CFTC positioning + US trade/tariff headline shocks | Pair Long BRL / Short MXN only when Brazilian fiscal noise calms |
Quantitative Carry-to-Volatility & Breakeven Depreciation Math#
Institutional FX desks calculate 3-Month Forward Breakeven Spot, Carry-to-ATM-Vol, and Vol-Target Position Sizing before allocating risk between BRL and MXN (funded either vs USD or JPY):
- Breakeven_ Cushion = ( Forward_3M - Spot ) / Spot [Quarterly % spot depreciation absorbed by carry]
- CarrytoVolRatio = AnnualizedCarrySpread / ImpliedVol3MATM
- Worked Comparison (Spot USD/BRL = 5.4000, yBRL = 12.15%; Spot USD/MXN = 19.2000, yMXN = 9.35%; i_USD = 3.85%):
- 1. USD/BRL Short: Ann. Carry = +8.30%; 3M Breakeven Cushion = +2.05% (Spot up to 5.5109 breaks even in 90D!)
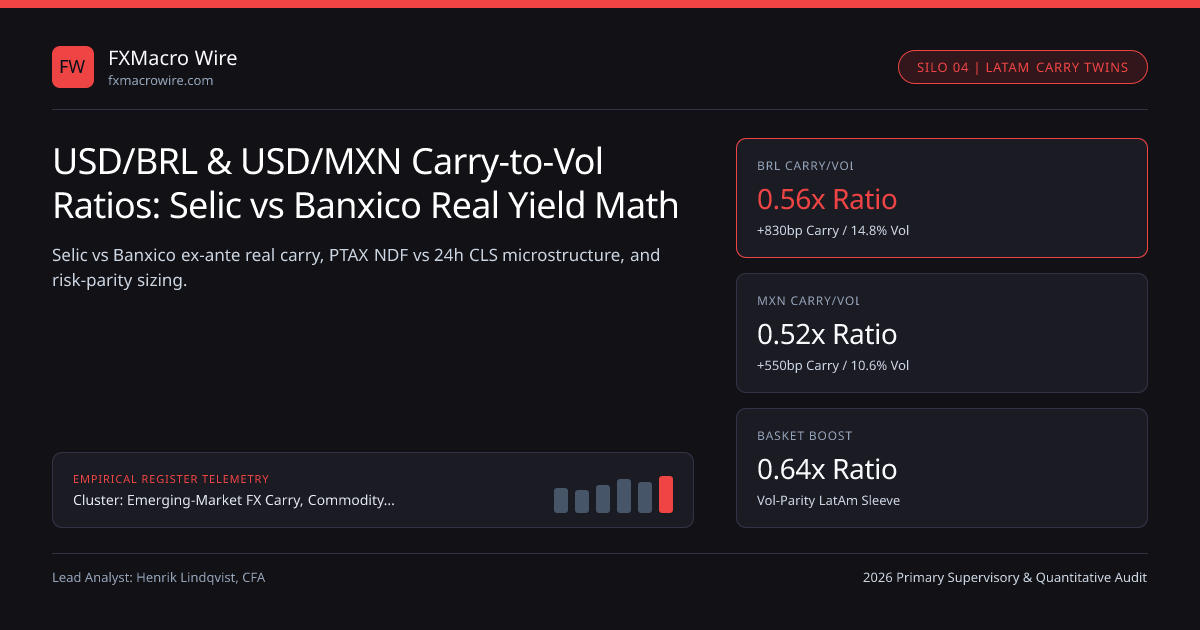
- With 3M ATM Implied Vol = 14.80% -> Carry/Vol = 8.30% / 14.80% = 0.561x
- 2. USD/MXN Short: Ann. Carry = +5.50%; 3M Breakeven Cushion = +1.36% (Spot up to 19.4615 breaks even in 90D)
- With 3M ATM Implied Vol = 10.60% -> Carry/Vol = 5.50% / 10.60% = 0.519x
Relative-Value Alpha: Trading the BRL/MXN Cross Without Broad Dollar Beta#
Notice why macro hedge funds love trading synthetic BRL/MXN (short USD/BRL NDF vs long equal-volatility USD/MXN forward):
- Because Brazil exports agricultural commodities and iron ore primarily to Asia (China credit impulse spillovers) while Mexico exports manufactured autos and electronics to the United States, the correlation between USD/BRL and USD/MXN sits near 0.58, leaving massive idiosyncratic dispersion!
- Whenever Brazil's 5Y sovereign CDS holds calm below 180 bps while BCB hikes Selic above Banxico, volatility-weighted Long BRL / Short MXN captures +280 bps of positive net carry while hedging out surprise FOMC dot-plot shocks!
Positioning Hygiene: Watching CFTC Peso Futures & B3 Foreign Institutional Net Shorts#
Before entering either leg, institutional desks cross-check two positioning gauges linked across our EM FX carry & REER hub guide, VIX/MOVE carry crash regime models, and fiscal dominance sovereign CDS paradox: (1) CME CFTC Leveraged + Asset Manager Net MXN Contracts (crowded above +$6B net long warns of violent yen-funded unwind cascades), and (2) B3 Daily Foreign Investor Cupom & USD Futures Net Open Interest published nightly in São Paulo across our EM FX carry & terms-of-trade hub.
Frequently asked questions
How is the daily Brazilian PTAX exchange rate calculated for USD/BRL NDF settlement?
Banco Central do Brasil queries accredited interbank FX dealers during four randomized two-minute windows between 10:00 and 13:00 BRT, trims the highest and lowest quotes, and publishes the arithmetic mean shortly after 13:15 BRT.
Why does USD/MXN often sell off during Asian trading hours when European or Asian news hits?
Because MXN is fully deliverable, CLS-settled, and deeply liquid 24 hours a day while most high-yielding EM currencies (BRL, INR, IDR, CLP) have closed onshore markets overnight, macro desks use MXN as a liquid proxy hedge.
How do institutional FX desks size BRL versus MXN in a combined LatAm carry sleeve?
Desks size by inverse 3-month implied volatility (risk parity)—holding roughly 0.72 units of BRL notional per 1.00 unit of MXN notional when BRL implied vol is 14.8% and MXN implied vol is 10.6%.
Why do Mexican worker remittances matter for USD/MXN valuation?
Over $60 billion per year in USD worker remittances converts steadily into pesos regardless of short-term interest-rate swings, creating structural corporate/retail USD supply that cushions Mexico’s current account.
Publication record
- Published
- 13 November 2026
- Updated
- 14 November 2026
- Author
- Henrik Lindqvist, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Henrik Lindqvist, CFA. (2026, November 14). USD/BRL & USD/MXN Carry-to-Vol Ratios: Selic vs Banxico Real Yield Math. FXMacro Wire. https://fxmacrowire.com/wire/usdbrl-usdmxn-real-carry-to-implied-volatility-ratiosRelated Em Carry Terms of Trade Shocks & Institutional Briefings
Explore Em Carry Terms of Trade Shocks Hub (20) →Em Carry Terms of Trade Shocks
Emerging-Market FX Carry, Commodity Terms of Trade & REER Valuation Guide (2026)Em Carry Terms of Trade Shocks
BIS Broad vs Narrow REER Indices: CPI vs ULC Currency MisalignmentsEm Carry Terms of Trade Shocks
Copper Terms-of-Trade Shocks: CLP, PEN & AUD/USD Exchange-Rate BetasEm Carry Terms of Trade Shocks
Onshore Forward vs Offshore NDF Basis Spreads: INR, KRW & BRL MechanicsEm Carry Terms of Trade Shocks
EUR/PLN, EUR/CZK & EUR/HUF: CEE-3 Real Carry & EU Recovery Fund FX FlowsEm Carry Terms of Trade Shocks
USD/ZAR Proxy Hedging, SARB Inflation Target Shift & PGM Export BetasEm Carry Terms of Trade Shocks
USD/INR Volatility Compression: RBI Two-Way NDF Intervention & FAR Bond FlowsEm Carry Terms of Trade Shocks
FX Carry Crash Skewness: VIX & ICE BofA MOVE Regime-Switching SignalsSafe Haven Capital Flow Regimes
The Dollar Smile Framework: US Exceptionalism vs Global Funding StressSafe Haven Capital Flow Regimes
US Treasury TIC Form SLT Flows: FX-Hedged vs Unhedged UST & Equity DemandSafe Haven Capital Flow Regimes
Broad Basic Balance (BBoP): Current Account + Net FDI as a G10 FX AnchorSafe Haven Capital Flow Regimes
Swiss Franc Real Safe-Haven Math: +9.5% Pharma Surplus, CPI Gap & EUR/CHF
FXMacro Wire Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.