
EUR/USD 3-Month XCCY Basis & G-SIB Year-End Balance-Sheet Window Dressing
Every September—when 3-month foreign exchange swaps first cross December 31st—EUR/USD ESTR-SOFR basis widens abruptly by 15 to 35 bps as European and US G-SIBs ration year-end balance-sheet capacity.
Every late September—on the exact morning when rolling 3-month T+2 foreign exchange swaps first span December 31st—the EUR/USD ESTR-SOFR cross-currency basis widens discontinuously by 15 to 35 basis points even when cash Eurozone and US money markets remain completely calm. Driven by Basel III Global Systemically Important Bank (G-SIB) capital surcharge snapshots audited on the final business day of the calendar year, dealer intermediation pullback creates a steep, tradeable "turn kink" across overnight, 1-week, and 3-month EUR/USD forward points.
How G-SIB Bucket Thresholds Ration December 31st FX Swap Capacity#
Under the Basel Committee on Banking Supervision (BCBS) G-SIB assessment methodology enforced across Eurozone banks by the European Central Bank, ACPR France, and BaFin Germany, systemic capital surcharges (ranging from 1.0% to 3.5% of Common Equity Tier 1) depend heavily on point-in-time December 31st balance-sheet size, intra-financial system assets/liabilities, and notional OTC derivatives.
When a French, Dutch, or German dealer intermediates a $5 billion EUR/USD FX swap over year-end, gross cash dollar borrowing and euro placement expand leverage-ratio exposure and interbank indicators right on the regulatory snapshot date. As detailed in our cross-currency swap basis and dollar funding hub, if crossing a G-SIB bucket boundary adds 50 bps of firm-wide CET1 capital across $600 billion of risk-weighted assets ($3 billion equity lockup!), FX swap desks rationally charge punitive implied dollar rates across the single overnight spanning December 31st to January 2nd.
Isolating Pure "Turn" Forward Points from Underlying ESTR-SOFR Rates#
Sophisticated treasury managers at European corporates and asset managers—routing forwards through Boursorama, Bolero, and Blocksize Capital under AMF and FSMA supervision—never mistake a late-September jump in 3-month EUR/USD basis for systemic European credit distress. Instead, they strip out the isolated 1-day turn premium (P_{turn}) embedded inside the 92-day swap contract.
Comparing this calendar anomaly against Covered Interest Parity Basel leverage shadow costs and Fed C7 standing swap line OIS + 25 bps ceilings explains why sovereign wealth funds and cash-rich US money-market accounts step in during mid-December to lend dollars over the turn via sponsored FICC repo and FX swaps, harvesting risk-free excess yield over ESTR.
| Tenor Crossing Dec 31st | Calendar Entry Date | Headline Annualized Basis | Implied 1-Day Turn Premium | Optimal Institutional Treasury Action |
|---|---|---|---|---|
| 6-Month EUR/USD Swap | Late June (T+2) | -18.5 bps (-4.3 bps turn drag) | ~78 bps annualized for 1-day | Lock 9M or 6M USD early to bypass Q4 crowd |
| 3-Month EUR/USD Swap | Late September (T+2) | -30.2 bps (-16.0 bps turn drag) | ~145 bps annualized for 1-day | Stagger maturities to Dec 28 or mid-January |
| 1-Month EUR/USD Swap | Late November (T+2) | -52.0 bps (-37.8 bps turn drag) | ~230 bps annualized for 1-day | Pre-fund cash USD via prime MMF or CP prior |
| Spot-Next Year-End Turn | Dec 29 / Dec 30 | -240.0 bps headline 2-day! | +240 bps over SOFR for Jan 2 | Tap ECB 7-day C7 USD tender if eligible |
Forward-Forward Decomposition of the Year-End Turn Rate#
Because an N-day FX swap spanning year-end combines (N - d_{turn}) normal trading days with d_{turn} year-end calendar days (typically 2 to 4 days depending on weekend alignment), forward desks extract the exact implied turn add-on (s_{turn}) in basis points and pips:
- s{turn} (annualized) = ( b{total,N} - b{clean} ) * ( N / d{turn} )
- Turn Pip Add-On = Spot * ( |s{turn}| * d{turn} / 360 )
- Worked Late-November 1-Month (N = 32 days, d_{turn} = 4 weekend-turn days) EUR/USD Example:
- Clean mid-November 1M basis b{clean} = -14.0 bps; Post-turn-crossing 1M basis b{total,32} = -46.0 bps
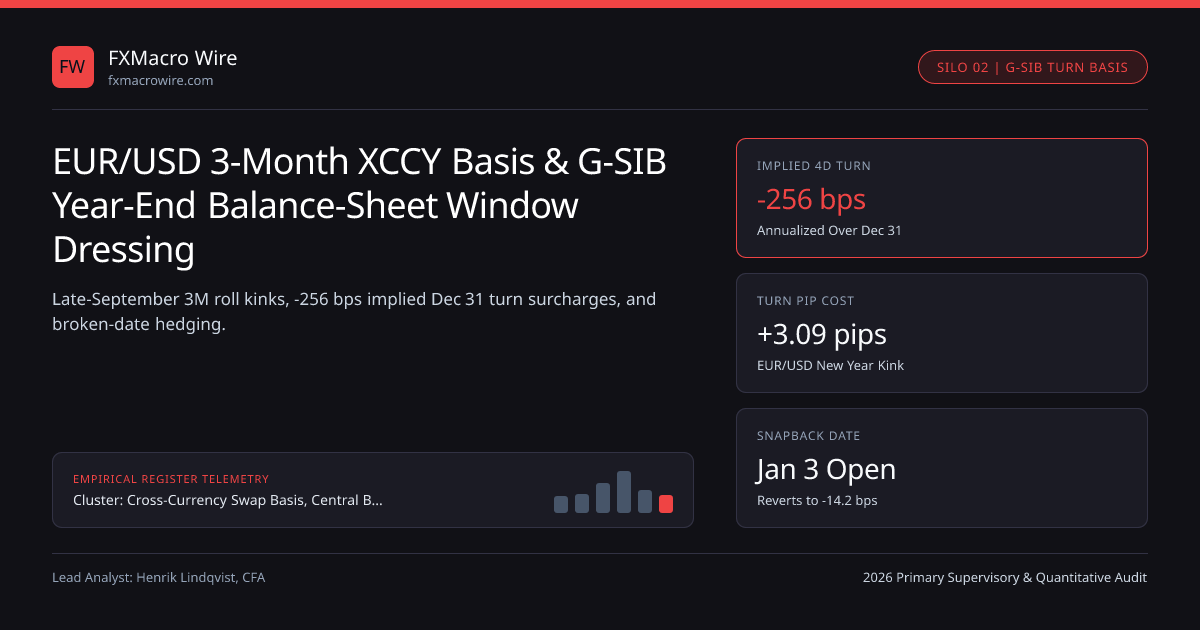
- Implied Turn Add-On s_{turn} = (-46.0 - (-14.0)) * (32 / 4) = -32.0 * 8 = -256.0 bps (+2.56% annualized USD surcharge!)
- At Spot EUR/USD = 1.0850: Turn Pip Cost = 1.0850 * (0.0256 * 4 / 360) = +0.000309 (+3.09 extra forward pips for 4 days)
Daily Averaging vs Point-in-Time Leverage Reporting Asymmetry#
Why do European banks pull back far more aggressively on quarter-ends and year-ends than US money-center banks? Federal Reserve Regulation Q / Supplementary Leverage Ratio (SLR) rules calculate bank leverage using quarterly daily averages, eliminating any incentive for New York banks to shrink exclusively on the final afternoon of the quarter. Conversely, several continental European and Asian reporting metrics retain quarter-end or year-end point-in-time snapshots, encouraging temporary compression of matched-book FX swaps on December 31st followed by immediate re-expansion on January 3rd.
Execution Playbook for Buy-Side FX Hedging Rolls#
Real-money overlay managers tracking our FX swap basis & dollar funding hub avoid paying peak December turn surcharges by splitting benchmark 3-month hedge rolls into broken-date maturities (for example rolling November 15th to February 15th, or laddering 6-month swaps in July and August) so maturity re-strikes never cluster inside the illiquid final two weeks of December.
Frequently asked questions
What is the year-end turn in EUR/USD FX forward and swap markets?
The year-end turn refers to the single spot-next or weekend settlement period spanning December 31st to the first business day of January, when G-SIB regulatory balance-sheet snapshots cause dealers to ration USD swap supply.
Why does the 3-month EUR/USD basis jump abruptly on a single day in late September?
With T+2 spot settlement, late September marks the exact roll date where a standard 3-month FX swap matures on January 2nd rather than December 30th, abruptly incorporating the December 31st G-SIB surcharge into the 3-month rate.
Does a wider December EUR/USD turn basis predict spot EUR/USD depreciation?
Usually not; predictable calendar window-dressing reflects regulatory balance-sheet accounting rather than credit default stress, and basis spreads typically snap back to -14 bps on January 3rd without driving spot EUR/USD.
How can US cash-rich institutions profit from year-end EUR/USD turn kinks?
Unconstrained dollar holders (such as sovereign wealth funds or prime funds) swap cash USD into euros on December 30th and place euros at the ECB or German repo, earning 200+ bps annualized excess pickup over SOFR for two to four days.
Publication record
- Published
- 14 November 2026
- Updated
- 14 November 2026
- Author
- Henrik Lindqvist, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Henrik Lindqvist, CFA. (2026, November 14). EUR/USD 3-Month XCCY Basis & G-SIB Year-End Balance-Sheet Window Dressing. FXMacro Wire. https://fxmacrowire.com/wire/eurusd-three-month-xccy-basis-gsib-turn-dressingRelated FX Swap Basis Dollar Funding & Institutional Briefings
Explore FX Swap Basis Dollar Funding Hub (20) →FX Swap Basis Dollar Funding
Cross-Currency Swap Basis, Fed Swap Lines & Global Dollar Funding Guide (2026)FX Swap Basis Dollar Funding
5-Year G10 Cross-Currency Basis & Corporate Yankee vs Reverse-Yankee ArbitrageFX Swap Basis Dollar Funding
Federal Reserve C7 Standing Dollar Swap Lines: OIS + 25 bps Ceiling MechanicsFX Swap Basis Dollar Funding
BIS Offshore Dollar FX Swap Debt & Non-Bank Rollover Stress MechanicsFX Swap Basis Dollar Funding
USD/JPY TONA-SOFR XCCY Basis & Japanese Megabank Dollar FundingFX Swap Basis Dollar Funding
Covered Interest Parity Deviations & Basel III Leverage Ratio Shadow CostsFX Swap Basis Dollar Funding
Yankee CDs, Commercial Paper & US Money-Market Fund FX Swap SpreadsFX Swap Basis Dollar Funding
NY Fed FIMA Repo Facility vs Central Bank FX Swap Lines: Sovereign USD PlumbingSovereign FX Reserves Intervention
Non-Traditional COFER Reserve Currencies: AUD, CAD, SGD, CNY & NordicsSovereign FX Reserves Intervention
Japan MoF FEFSA Sterilized Yen Intervention: T+2 BoJ Account MechanicsSovereign FX Reserves Intervention
SNB Sight-Deposit Tiering & Two-Way Foreign Exchange Reserve ManagementSovereign FX Reserves Intervention
Central Bank Physical Gold Accumulation, Allocated Vaulting & BIS Gold Swaps
FXMacro Wire Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.