
SA-CCR Counterparty Credit Capital Charges on Institutional FX Swap Books
Replacing the legacy Current Exposure Method, Basel III’s Standardized Approach for Counterparty Credit Risk (SA-CCR) applies a 4.0% FX supervisory factor and 1.4x alpha multiplier that reshapes unmargined buy-side FX swap pricing.
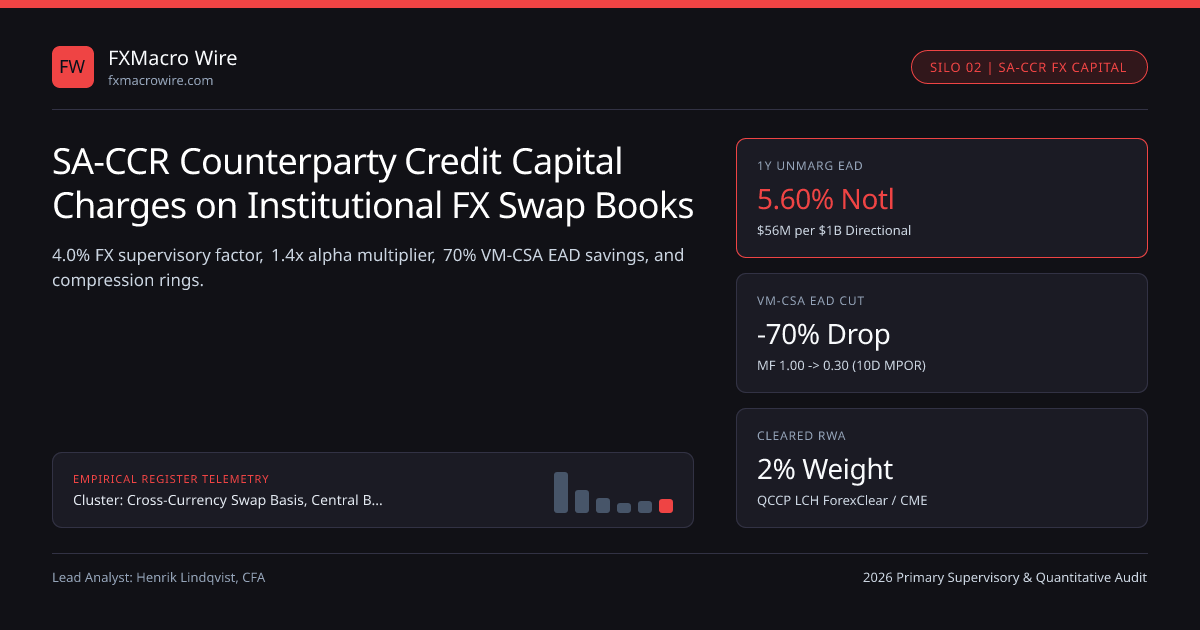
Implemented across European banks under CRR II (Regulation (EU) 2019/876) and across US G-SIBs in January 2022, the Standardized Approach for Counterparty Credit Risk (SA-CCR) governs both Risk-Weighted Assets (RWA) and Basel III Leverage Exposure across FinDB's BIS $9.6 Trillion Daily OTC FX Market. Because SA-CCR assigns a flat 4.0% Supervisory Factor (SF_{FX} = 4%) to every currency pair and multiplies Replacement Cost (RC) plus Potential Future Exposure (PFE) by an alpha factor of 1.4x, directional one-way pension and corporate FX forward books incur dramatically higher dealer capital charges than cleared or CSA-margined swaps!
Why SA-CCR Penalizes Unmargined Directional Buy-Side FX Forward Books#
Under the Basel Committee on Banking Supervision (BCBS) CRE52 standard enforced by the European Central Bank, BaFin, ACPR, and FINMA, SA-CCR groups all FX trades under a single ISDA Master Agreement into distinct currency-pair hedging sets (for example, all EUR/USD trades sit in one hedging set; all GBP/USD trades sit in a separate hedging set with zero cross-pair PFE offset!).
Inside each currency-pair hedging set:
- Interbank Dealers hold two-way long and short EUR/USD forwards that net down by 90% to 98%, collapsing SA-CCR PFE close to zero.
- Real-Money Pension Funds, Insurers & Corporates hold 100% directional one-way short-USD / long-EUR hedges, receiving 0% directional netting! Unless the client signs a daily two-way Variation Margin Credit Support Annex (VM-CSA)—which cuts the SA-CCR Maturity Factor (
MF) by ~70%—the dealer bank must hold full unmargined1.4 * 4.0% = 5.6%exposure add-on per maturity-adjusted dollar of notional!
Connecting SA-CCR math to our cross-currency swap basis hub, Basel III CIP leverage hurdles, and UMR Phase 6 initial margin thresholds explains why dealers quote 3 to 9 bps tighter 3-month FX swap rates to clients who post daily cash variation margin or clear via LCH ForexClear / Eurex!
Tiered Dealer Pricing Across Unmargined, VM-CSA, and CCP-Cleared FX Books#
Institutional FX prime brokers, clearing members, and multi-dealer execution venues—operating across CSSF, CBI, and AFM frameworks alongside Blocksize Capital, Bequant, and CMC Central—segment buy-side counterparties into four distinct capital-cost tiers reflected directly in forward-point skews and 5-year XCCY swap spreads:
| Counterparty Margin & Clearing Tier | SA-CCR Maturity Factor (MF) | Counterparty RWA Weight | SA-CCR EAD on $1B 1Y FX Swap | Dealer Capital Charge Pass-Through |
|---|---|---|---|---|
| Unmargined Corporate / Sovereign | 1.000 (sqrt(1Y/1Y)) | 50% - 100% RWA | $56.0M (5.60% of notional!) | +8.5 to +14.0 bps KVA/CVA drag |
| Unmargined Pension / UCITS (3M Roll) | 0.500 (sqrt(0.25Y)) | 20% - 50% RWA | $28.0M (2.80% of notional) | +4.0 to +6.5 bps roll widening |
| Bilateral Daily Cash VM-CSA | 0.194 (1.5*sqrt(10/250)) | 20% - 50% RWA | $10.86M (1.09% -> -61% cut!) | +1.4 to +2.2 bps tight institutional |
| QCCP Cleared (LCH ForexClear / CME) | 0.134 (5-day MPOR) | 2% QCCP RWA! | $7.50M + 2% RWA (~95% RWA cut!) | +0.5 to +0.9 bps interbank screen |
Step-by-Step Basel CRE52 SA-CCR EAD & KVA Pricing Calculation#
Under Basel CRE52, Exposure at Default (EAD) for a directional single-pair FX forward portfolio at inception (RC = 0, PFE multiplier = 1.0) equals 1.4 * 0.04 * |Notional_{USD}| * MF. Let's compare an unmargined 1-year $1.0 billion EUR/USD hedge against a daily Cash VM-CSA (10-business-day Margin Period of Risk, MPOR = 10/250):
- MF_{margined} = 1.5 * sqrt( MPOR / 250 ) (for daily VM-CSA, MPOR = 10 days -> MF = 1.5 * 0.20 = 0.30!)
- EAD{SA-CCR} = 1.4 * ( RC + 0.04 * |AdjustedNotional| * MF )
- Worked $1.0 Billion 1-Year Directional EUR/USD Hedge Capital Charge (50% Counterparty RWA, 12% CET1 @ 12% Hurdle):
- Case A — Unmargined 1Y Forward (MF = 1.00):
- EAD = 1.4 * (0 + 0.04 * $1,000M * 1.00) = $56.00M -> RWA = $28.00M -> Leverage Cap (4.5%) = $2.52M vs RWA Cap = $3.36M
- Binding RWA Capital Cost (KVA) = $3.36M * 12% = $403,200/yr = 4.03 bps pure KVA (+ ~5.5 bps CVA = 9.53 bps total!)
- Case B — Daily Cash VM-CSA (MPOR = 10/250 -> MF = 1.5 * sqrt(0.04) = 0.30):
- EAD = 1.4 * (0.04 * $1,000M * 0.30) = $16.80M (-70% EAD drop!) -> KVA drops to 1.21 bps (saves >8.3 bps/yr with ~0 CVA!)
(Note: Under Basel CRE52.50, `MF_{margined} = 1.5 sqrt(10/250) = 0.30 bilaterally and 1.5 * sqrt(5/250) = 0.212` for client-cleared 5-day MPOR trades—cutting 1-year EAD by 70% to 79%!)*
Multilateral FX Compression & Capitolis / TriOptima Novation Networks#
How does the interbank market keep SA-CCR leverage capital from paralyzing $9.6T/day FX turnover? Third-party balance-sheet optimization platforms (such as Capitolis and OSTTRA TriOptima) run weekly multilateral FX forward compression cycles across 25+ dealer banks and buy-side prime brokers—identifying closed loops of offsetting EUR/USD and USD/JPY forwards and tearing up or novating trillions of dollars in gross notional without altering a single participant's net market exposure!
Negotiating Two-Way VM-CSAs for Institutional FX Overlays#
Buy-side investment committees rolling >$500 million in directional FX hedges should prioritize onboarding zero-threshold daily Cash VM-CSAs (or sponsored FX clearing) ahead of negotiating headline voice spreads, capturing 4 to 7 bps of structural SA-CCR KVA savings documented across our FX swap basis & dollar funding hub.
Frequently asked questions
Does Basel III SA-CCR allow offsetting a long EUR/USD forward against a short GBP/USD forward?
No. Under BCBS CRE52, each currency pair forms a separate hedging set with zero PFE correlation offset across different pairs—even highly correlated pairs like EUR/USD and USD/CHF!
Why do physically settled FX swaps still incur SA-CCR capital charges if exempted from mandatory clearing?
While physically settled FX swaps and forwards are exempt from mandatory central clearing and UMR Initial Margin, banks must still hold SA-CCR Counterparty Credit Risk RWA and Leverage Ratio capital against them.
Why does SA-CCR use a 1.4x alpha multiplier and could regulators lower it?
The 1.4x alpha multiplier originated in internal-model IMM calibration for wrong-way and granularity risk; both EU CRR III debates and US Basel III Endgame proposals have evaluated setting alpha = 1.0x for commercial end-users.
How does FX trade compression reduce bank cross-currency swap spreads?
Multilateral compression tears up redundant offsetting forward legs across dealer rings, shrinking gross SA-CCR PFE and G-SIB notional scores so dealers can quote tighter spreads to end clients.
Publication record
- Published
- 14 November 2026
- Updated
- 14 November 2026
- Author
- Henrik Lindqvist, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Henrik Lindqvist, CFA. (2026, November 14). SA-CCR Counterparty Credit Capital Charges on Institutional FX Swap Books. FXMacro Wire. https://fxmacrowire.com/wire/sa-ccr-counterparty-capital-charges-fx-swap-booksRelated FX Swap Basis Dollar Funding & Institutional Briefings
Explore FX Swap Basis Dollar Funding Hub (20) →FX Swap Basis Dollar Funding
Cross-Currency Swap Basis, Fed Swap Lines & Global Dollar Funding Guide (2026)FX Swap Basis Dollar Funding
UMR Phase 6 Initial Margin Rules: FX Forwards vs Cross-Currency SwapsFX Swap Basis Dollar Funding
SOFR-ESTR Mark-to-Market Resetting Cross-Currency Basis Swap ConventionsFX Swap Basis Dollar Funding
Scandinavian STIBOR & NIBOR Year-End FX Swap USD Squeezes (SEK & NOK)FX Swap Basis Dollar Funding
USD/SGD SORA-SOFR FX Swap Points & Asian Dollar Funding MechanicsFX Swap Basis Dollar Funding
EUR/USD 3-Month XCCY Basis & G-SIB Year-End Balance-Sheet Window DressingFX Swap Basis Dollar Funding
5-Year G10 Cross-Currency Basis & Corporate Yankee vs Reverse-Yankee ArbitrageFX Swap Basis Dollar Funding
Federal Reserve C7 Standing Dollar Swap Lines: OIS + 25 bps Ceiling MechanicsSovereign FX Reserves Intervention
IMF Assessing Reserve Adequacy (ARA) Metric vs Guidotti-Greenspan RulesSovereign FX Reserves Intervention
Off-Balance-Sheet Central Bank FX Forwards, Swaps & IMF SDDS Reporting LagsSovereign FX Reserves Intervention
Norges Bank Daily NOK FX Conversions & $1.8T NBIM Petroleum Fiscal RuleSovereign FX Reserves Intervention
G7 Coordinated FX Intervention vs Unilateral Strikes & NY Fed Rate Checks
FXMacro Wire Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.