
Em Carry Terms of Trade Shocks
Brazil BCB Swap Cambial & Cupom Cambial (DDI): Onshore BRL USD Liquidity
Unlike most emerging markets wherespot interbank banks lead price discovery, Brazilian real (USD/BRL) exchange-rate formation centers on B3 futures and Banco Central do Brasil’s $100B+ Swap Cambial derivative book.
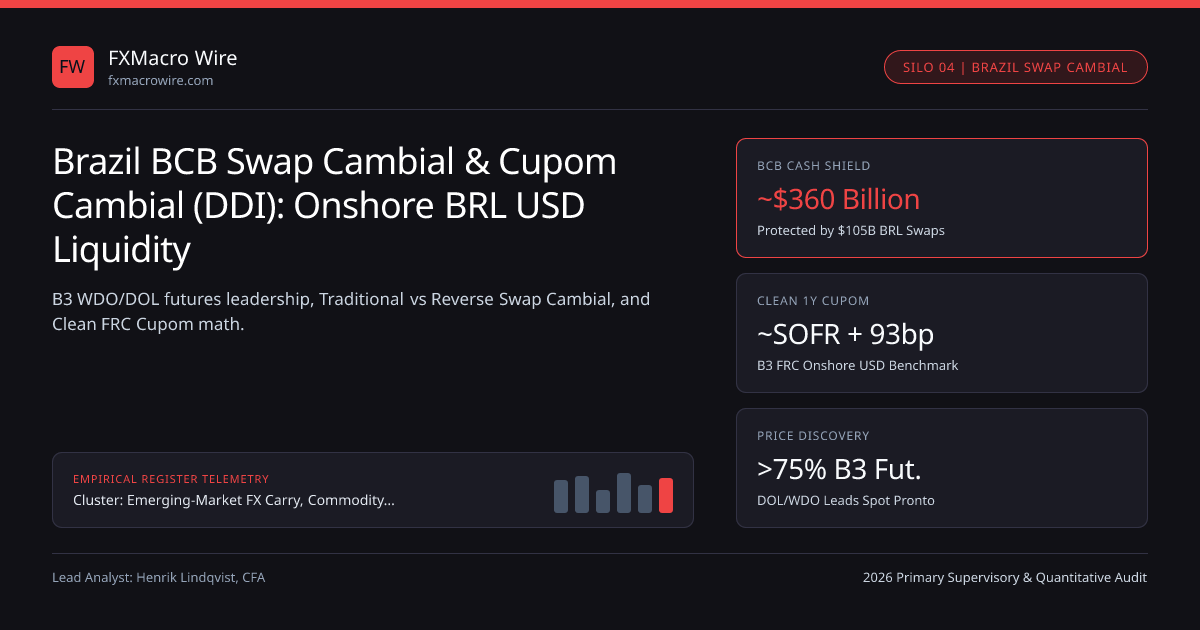
Attempt to trade USD/BRL using standard G10 interbank spot intuition and you will be blindsided on day one! In Brazil, interbank spot USD/BRL ("Dólar Pronto") trades a mere fraction of the daily volume cleared on São Paulo's B3 exchange in 1-month Dollar Futures (DOL & mini-WDO — often $35B–$55B/day!)—making Brazil the only major FX market on Earth where exchange-listed futures lead spot price discovery inside global OTC FX turnover!
Even more remarkably, when Banco Central do Brasil (BCB) intervenes to quell real depreciation, it rarely touches its ~$355B–$370B cash FX reserves (global sovereign reserves) unless an acute USD cash Funding drought strikes! Instead, BCB auctions BRL-settled "Swaps Cambiais" (Central Bank FX Swaps) that supply synthetic USD forward protection while keeping every dollar of sovereign US Treasury reserves intact!
Demystifying BCB "Traditional" vs "Reverse" Swap Cambial Nomenclature!#
Warning for global macro analysts trained under ECB, BCBS, or IOSCO swap conventions (routing Latin American NDFs via Blocksize Capital, Bequant, and B2BX Exchange): Brazilian Swap Cambial terminology is named from the CENTRAL BANK'S perspective—the exact opposite of intuitive street slang:
- Traditional BCB Swap Cambial (Supports / Strengthens BRL!): BCB pays USD exchange-rate variation + onshore USD interest (Cupom Cambial) and receives domestic overnight CDI (Selic-linked) interest, settled 100% in Brazilian reais! Effect: Private banks and corporates receive synthetic long-USD hedge protection from BCB—so they stop buying B3 Dollar Futures, pulling USD/BRL down AND pushing onshore Cupom Cambial rates lower!
- Reverse BCB Swap Cambial (Weakens BRL / Absorbs Inflows): BCB receives USD variation + Cupom and pays CDI—acting economically like a synthetic USD purchase during real-appreciation booms!
- Dollar Line Auctions (Leilão de Linha): When corporates need actual physical greenback wires over year-end dividend remittance seasons (rather than BRL-settled hedges!), BCB auctions spot USD with a mandatory 3-to-6-month repurchase agreement—injecting physical onshore USD cash temporarily!
Decoding "Cupom Cambial" (DDI vs FRC): Brazil's Onshore US Dollar Interest Rate!#
What is Cupom Cambial? Simply the onshore US dollar interest rate inside Brazil—implied by the difference between Brazil's overnight CDI rate (252 business-day compounding!) and the forward depreciation embedded in B3 USD/BRL futures!
| Brazilian B3 FX Instrument | Ticker & Day-Count Rule | Economic Function | Critical Institutional Nuance |
|---|---|---|---|
| 1st-Month Dollar Future | DOL ($50k) / WDO ($10k), settles 1st bus. day | #1 liquidity pool ($40B+/day); leads offshore NDFs | Only 1st contract (c1) is ultra-liquid; rolls on last day via DR1 |
| Dirty Cupom Cambial | DDI (Linear Act/360 USD vs 252 Bus-Day CDI) | Implied onshore USD yield from yesterday’s PTAX! | Distorted intraday ("dirty") whenever today’s spot moves far from T-1 PTAX! |
Clean Cupom (FRA de Cupom) | FRC (Forward starting from today’s PTAX) | True clean onshore USD interest rate (SOFR + Brazil spread) | Always watch FRC (not DDI) to gauge real onshore USD cash scarcity! |
Casado (Spot vs c1 Basis) | Simultaneous Spot USD vs DOLc1 trade | Bridges physical spot greenbacks to B3 futures curve | Blows out in December when multinationals wire physical USD dividends abroad |
Exact Compound-vs-Linear Brazilian Cupom Cambial Formula (252 Bus. Days vs Act/360!)#
Never apply naive Act/360 minus Act/360 subtraction in Brazil! Domestic Brazilian DI / CDI futures compound exponentially over 252 business days (du), whereas Cupom Cambial quotes linearly over dc / 360 calendar days! Here is the exact B3 arbitrage identity connecting Spot/PTAX, DI1, DOL, and Clean Cupom (FRC):
- CupomCleanFRC = [ ( ( 1 + CDIAnn )^( du / 252 ) ) / ( FDOL / S_Spot ) - 1 ] * ( 360 / dc )
- Worked 1-Year (du = 252 business days, dc = 365 calendar days) São Paulo Arbitrage Check:
- Suppose CDI_1Y = 12.40%, Spot USD/BRL = 5.4000, 1Y Implied Forward = 5.7920 (+7.259% forward depreciation):
- 1 + CDI_1Y = 1.1240; Divide by (5.7920 / 5.4000 = 1.072593) -> 1.1240 / 1.072593 = 1.047928
- Clean Cupom (FRC_1Y) = (1.047928 - 1) * (360 / 365) = 4.727%!
- Compare vs 1Y USD SOFR (3.80%) -> Onshore Brazil USD Spread = +92.7 bps (Tracks Brazil 1Y sovereign risk closely!)
The Hidden Fiscal Catch of Swap Cambial Losses!#
Why can't BCB simply issue $300 billion of Traditional Swap Cambial contracts indefinitely during a fiscal crisis (fiscal dominance sovereign CDS paradox)? Because Traditional Swaps settle P&L in Brazilian reais directly into BCB's net interest bill! If BCB is short $110 billion of synthetic USD via Swap Cambial and USD/BRL jumps +15% on fiscal fears, BCB pays ~R$90 billion in cash swap losses to private holders—expanding Brazil's consolidated nominal fiscal deficit at the exact worst moment!
Reading FRC vs Swap Cambial Signals for USD/BRL Carry Timing#
Institutional desks combining our EM FX carry & REER hub guide, USD/BRL vs USD/MXN carry-to-vol models, and offshore PTAX NDF basis mechanics watch 1Y Clean Cupom (FRC - US SOFR) daily: when USD/BRL spikes on global noise while FRC - SOFR stays calm near +90 bps, domestic capital is NOT fleeing physical dollars—offering high-conviction USD/BRL NDF carry entries across our EM FX carry & terms-of-trade hub!
Frequently asked questions
Why is a BCB "Traditional Swap Cambial" supportive for the Brazilian real?
In a Traditional Swap Cambial, Banco Central do Brasil takes the short-USD / long-BRL side (paying USD exchange-rate change plus Cupom and receiving domestic CDI), absorbing private corporate USD hedging demand.
What is the difference between BCB Swap Cambial and a BCB Dollar Line ("Leilão de Linha") auction?
Swap Cambial contracts settle purely in Brazilian reais and satisfy derivative hedging demand, whereas a Linha auction sells actual physical spot US dollars from reserves paired with a repurchase agreement to relieve physical greenback wire shortages.
Why does Dirty Cupom (DDI) swing wildly intraday when USD/BRL moves 1.5%?
Because DDI accrues from the prior business day’s settled PTAX fixing; an intraday jump in spot USD/BRL inflates the apparent short-dated return until B3’s FRC (FRA de Cupom) strips out the T-1 PTAX leg.
How did Brazil’s OECD-aligned FX reform change the IOF tax on foreign exchange transactions?
Brazil enacted Law 14,286 modernizing foreign exchange rules and phased out punitive IOF financial transaction taxes on cross-border FX and derivative flows toward 0% by 2028-2029.
Publication record
- Published
- 13 November 2026
- Updated
- 15 November 2026
- Author
- Henrik Lindqvist, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Henrik Lindqvist, CFA. (2026, November 15). Brazil BCB Swap Cambial & Cupom Cambial (DDI): Onshore BRL USD Liquidity. FXMacro Wire. https://fxmacrowire.com/wire/brazil-bcb-swap-cambial-cupom-cambial-brl-liquidityRelated Em Carry Terms of Trade Shocks & Institutional Briefings
Explore Em Carry Terms of Trade Shocks Hub (20) →Em Carry Terms of Trade Shocks
Emerging-Market FX Carry, Commodity Terms of Trade & REER Valuation Guide (2026)Em Carry Terms of Trade Shocks
Diversified FX Carry Funding Baskets: JPY, CHF, EUR & CNH OptimizationEm Carry Terms of Trade Shocks
Fiscal Dominance & Sovereign CDS: When EM Central Bank Hikes Weaken FX!Em Carry Terms of Trade Shocks
USD/TWD & Taiwan Life Insurers: $700B USD Bond Book, Proxy Hedges & NDFsEm Carry Terms of Trade Shocks
USD/TRY Orthodox Carry Pivot: CBRT Swap Unwind, Real Lira Appreciation & REEREm Carry Terms of Trade Shocks
China Credit Impulse, CFETS RMB Basket & ASEAN / LatAm EM FX SpilloversEm Carry Terms of Trade Shocks
Non-CLS Emerging-Market FX Settlement: Herstatt Risk & Nostro Pre-Funding DragEm Carry Terms of Trade Shocks
USD/BRL & USD/MXN Carry-to-Vol Ratios: Selic vs Banxico Real Yield MathSafe Haven Capital Flow Regimes
Cross-Border M&A Deal-Contingent FX Forwards: Pricing Regulatory Tail RiskSafe Haven Capital Flow Regimes
Solvency II 25% FX Capital Charge: Why European Insurers Hedge 95% of USDSafe Haven Capital Flow Regimes
FX 25-Delta Risk Reversals & Butterflies: Reading Safe-Haven Tail SkewSafe Haven Capital Flow Regimes
Sovereign Wealth Fund & Petrodollar Recycling: ADIA, PIF, QIA & NBIM FX Flows
FXMacro Wire Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.