
Safe Haven Capital Flow Regimes
Eurozone TARGET2 (T2) Balances: Reading Intra-Euro Capital Flight & EUR/USD
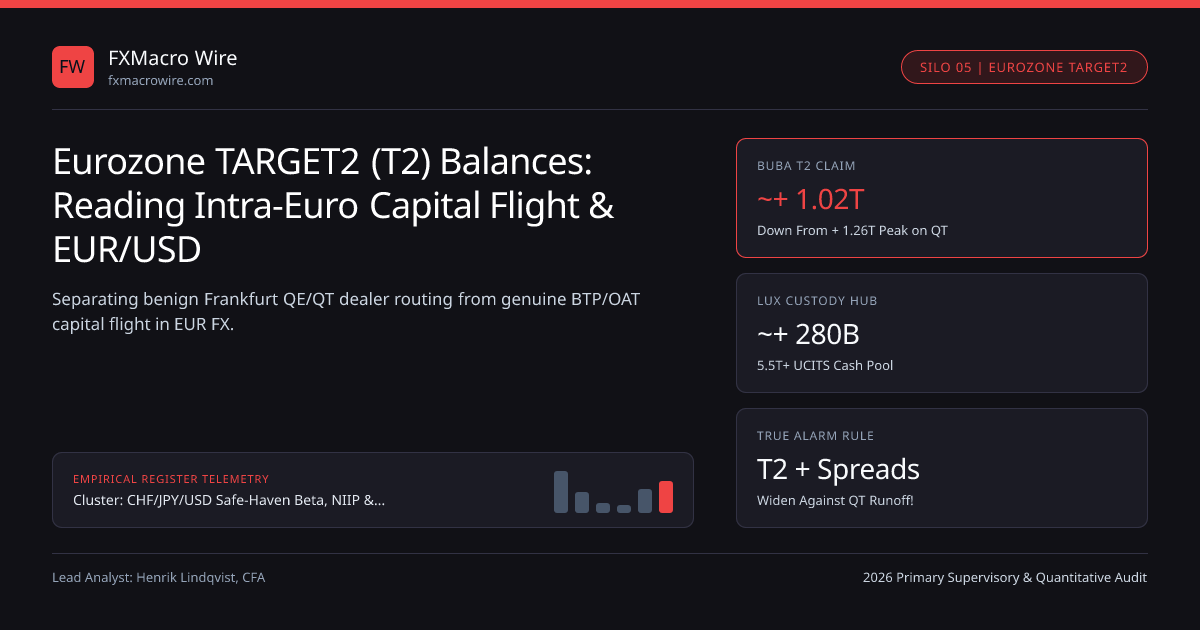
Exceeding €1.1 trillion in Bundesbank claims at peak, Eurozone TARGET2 central bank settlement balances act as an X-ray of cross-border Eurosystem liquidity—provided strategists distinguish benign ECB QE settlement routing from genuine deposit flight.
Inside the Eurosystem—linking the European Central Bank with twenty National Central Banks including the Deutsche Bundesbank, Banque de France (ACPR), Banca d'Italia (CONSOB ecosystem), Banco de España (BdE), De Nederlandsche Bank, and Central Bank of Luxembourg (CSSF)—every cross-border commercial bank euro wire settles instantaneously inside T2 (formerly TARGET2: Trans-European Automated Real-time Gross Settlement Express Transfer).
When an Italian depositor wires €10 million from Milan to a German bank in Frankfurt, no gold or Treasuries move between Rome and Frankfurt: instead, Banca d'Italia incurs a -€10M TARGET2 Liability to the ECB, and Deutsche Bundesbank records a +€10M TARGET2 Claim on the ECB! At peak, Germany's Bundesbank TARGET2 claim topped +€1.26 TRILLION while Italy and Spain carried -€680B and -€500B debits—sparking fierce market debates over Eurozone redenomination risk and EUR/USD / EUR/CHF tail pricing!
Crucial Institutional Distinction: Crisis Capital Flight (2011–12) vs Mechanical ECB QE Routing (2015–22)!#
Before shorting EUR/USD at Blocksize Capital, Boursorama, or Bolero because Italy's TARGET2 deficit widened by -€40 billion, BIS and ECB monetary plumbing papers prove you MUST distinguish TWO completely different causes of TARGET2 divergence:
- Malign Regime — Private Deposit & Interbank Flight (2011–2012 Sovereign Crisis): Foreign banks refuse to roll repo to Italian/Spanish banks AND domestic savers wire deposits to Germany/Luxembourg -> TARGET2 diverges alongside exploding BTP-Bund spreads (>450 bps) -> BEARISH EUR/USD & EUR/CHF!
- Benign Regime — Mechanical ECB QE Custodial Routing (2015–2022 APP/PEPP & 2023–2026 QT Reversal!): When Banca d'Italia bought €20B of Italian BTPs during QE from a London global bank whose Eurozone T2 correspondent account sits at Bundesbank in Frankfurt, Banca d'Italia wired €20B to Frankfurt—mechanically widening Italy's T2 debit and Germany's T2 credit with ZERO Italian capital flight! And as ECB Quantitative Tightening (QT) runs off APP/PEPP bonds in 2025–2026, TARGET2 imbalances have shrunk by hundreds of billions in reverse!
Comparing the Three Historical TARGET2 Regimes for FX Traders#
Audit all four market observables simultaneously before firing a Euro redenomination tail hedge:
| Eurozone Regime Era | TARGET2 Balance Trend | 10Y BTP-Bund & OAT-Bund | Retail Resident Deposits | Spot EUR/USD & EUR/CHF Signal |
|---|---|---|---|---|
| 2011–Jul 2012 (Euro Crisis) | Exploded 0 -> €1.0T gap in 18 mos | 350 – 550 bps (Acute stress!) | Spanish/Greek/Italian bank outflows | Violently Bearish EUR (Draghi OMT bottom) |
| 2015–2021 (ECB QE Routing) | Widened steadily to €1.26T | Calm (100 – 160 bps) | Stable / Growing domestic deposits | Neutral FX Plumbing (London dealers clear via BuBa) |
| Mar–Sep 2020 (Pandemic) | Spiked +€260B in 4 months | Briefly hit 270bp -> crushed by PEPP | Corporate precautionary cash draws | Bullish EUR rebound (1.07 -> 1.22 once PEPP/NGEU hit!) |
| 2024–2026 (ECB QT + TPI Era) | Contracting steadily via bond runoff | Anchored (~115–145bp BTP; watching OATs) | High retail BTP Valore bond uptake! | Constructive EUR unless T2 spikes against QT trend! |
Quantitative National Central Bank Balance-Sheet Accounting Identity#
How do ECB watchers prove mathematically whether a -€25 billion monthly drop in Banca d'Italia's TARGET2 balance came from genuine private capital flight vs official monetary operations? Use the NCB Balance-Sheet Identity:
- TruePrivateFlightSignal = Delta TARGET2Italy + DeltaBancadItaliaNetQE [During QT, Net_QE is negative!]
- Worked 2026 ECB QT Era Early-Warning Detection:
- During passive ECB QT, Italian Treasury redeems €12B/month of maturing BTPs held by foreign/Frankfurt-cleared banks ->
- Baseline QT Effect: Italy TARGET2 SHOULD IMPROVE (shrink deficit) by ~ +€8B to +€12B/month!
- WARNING TRIGGER: If Italy or France TARGET2 WORSENS by -€35B in a single month DURING QT,
- True Private Capital Flight = -€35B - (+€10B expected QT shrink) = -€45 Billion sudden private exit!! -> Short EUR/CHF!
Why Luxembourg (+€280B) & Netherlands (+€90B) Sit Alongside Bundesbank as Giant T2 Creditors!#
Notice a crucial institutional detail: Luxembourg (GDP ~€85B!) holds nearly +€280 billion in positive TARGET2 claims—over 320% of Luxembourg's GDP! Why? Not because Luxembourgers export €280B of steel—but because CSSF-regulated Luxembourg UCITS funds manage over €5.5 trillion of pan-European investor savings, parking uninvested euro cash balances at custodian banks in Luxembourg's central bank (BCL)!
Integrating TARGET2 Surveillance With ECB TPI & Post-NIRP Flows#
Combine monthly Bundesbank / Banca d'Italia TARGET2 releases (published by the 7th business day of each month!) with our safe-haven FX & BoP hub guide, EUR/CHF sovereign fragmentation hedging, and post-NIRP Eurozone bond repatriation—respecting the Euro's structural bid during calm QT compression while owning cheap 3-month EUR/CHF puts whenever TARGET2 diverges against QT seasonality across our safe-haven FX & capital-flow regimes hub!
Frequently asked questions
Can a Eurozone National Central Bank "run out" of TARGET2 credit or face a margin call?
No: inside the Eurosystem monetary union, intra-Eurosystem T2 liabilities carry no maturity date, no collateral haircut limit, and no ceiling so long as commercial banks pledge eligible collateral at their home NCB.
Why did London banks’ bond sales to Banca d’Italia increase GERMANY’S TARGET2 balance?
After Brexit and even prior, UK and US investment banks without direct Eurozone branches maintain their primary T2 euro clearing accounts at their Frankfurt subsidiaries under the Deutsche Bundesbank.
How did Italy’s retail "BTP Valore" bond issuances help shrink Italy’s TARGET2 deficit?
Italian households bought tens of billions of euros of domestic BTPs as ECB-held bonds matured under QT, replacing Eurosystem central bank financing with sticky domestic private savings.
What ECB tool caps extreme TARGET2 and sovereign bond spread blowouts since July 2022?
The Transmission Protection Instrument (TPI) authorizes the ECB to purchase unlimited secondary-market bonds of any compliant Eurozone state experiencing unwarranted, disorderly market dynamics.
Publication record
- Published
- 13 November 2026
- Updated
- 14 November 2026
- Author
- Henrik Lindqvist, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Henrik Lindqvist, CFA. (2026, November 14). Eurozone TARGET2 (T2) Balances: Reading Intra-Euro Capital Flight & EUR/USD. FXMacro Wire. https://fxmacrowire.com/wire/eurozone-target2-balances-portfolio-flight-signalsRelated Safe Haven Capital Flow Regimes & Institutional Briefings
Explore Safe Haven Capital Flow Regimes Hub (20) →Safe Haven Capital Flow Regimes
G10 Safe-Haven FX Beta, NIIP & Balance-of-Payments Capital Flow Guide (2026)Safe Haven Capital Flow Regimes
US Exorbitant Privilege & NIIP Valuation Effects Across Dollar CyclesSafe Haven Capital Flow Regimes
Energy Supply Shocks & the Safe-Haven Flip: Why JPY & EUR Broke in StagflationSafe Haven Capital Flow Regimes
UK Twin Deficits & 31.4% Foreign Gilt Share: Modeling Sterling’s Risk BetaSafe Haven Capital Flow Regimes
CFTC TFF FX Positioning: Leveraged Funds vs Asset Managers & Pain TradesSafe Haven Capital Flow Regimes
Global M2 Liquidity Impulse & Central Bank Reserves: High-Beta AUD, NZD & SEKSafe Haven Capital Flow Regimes
Cross-Border M&A Deal-Contingent FX Forwards: Pricing Regulatory Tail RiskSafe Haven Capital Flow Regimes
Solvency II 25% FX Capital Charge: Why European Insurers Hedge 95% of USDRegulatory Compliance
Revolut Secures ECB Approval for Major European Restructuring and French Expansion - FF NewsDigital Currency
ECB warns legislative delays could postpone digital euro launchDigital Currencies
Piero Cipollone: Cash and the digital euro: two sides of the same coinMarket Insights
Yuan Rally Likely to Cool, Not Reverse
FXMacro Wire Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.