
Sovereign FX Reserves Intervention
Central Bank Physical Gold Accumulation, Allocated Vaulting & BIS Gold Swaps
Sustaining historic net purchases above 1,000 metric tons annually, emerging-market and European central banks use allocated physical gold bullion to insulate sovereign reserves from sanction freezes while monetizing liquidity via BIS gold swaps.
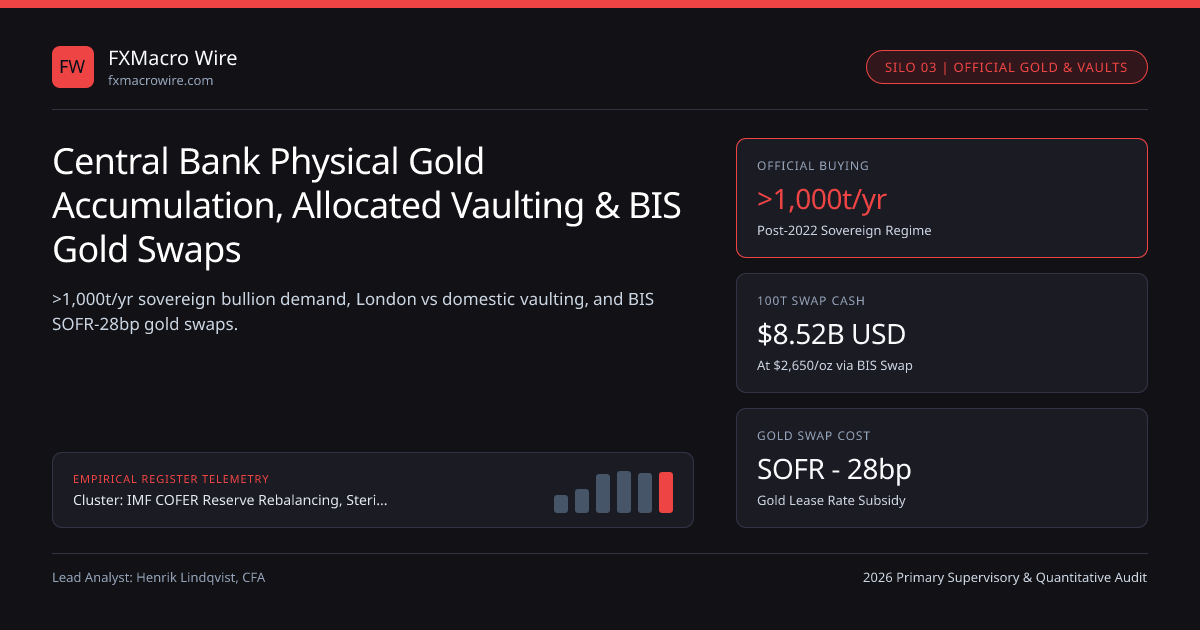
Surpassing every post-1971 Bretton Woods record, global monetary authorities have accumulated over 1,000 metric tons of physical gold bullion annually since 2022—lifting official sector gold holdings past 36,800 metric tons (~18% to 21% of total international reserves including gold) alongside FinDB's $13.22T IMF COFER FX Reserve Stock. Crucially, modern central bank bullion buying decoupled gold prices from their classic negative correlation with real US 10-year TIPS yields and DXY: sovereign reserve managers buy allocated bullion not for coupon carry, but as the sole monetary asset carrying zero foreign-sovereign counterparty or G7 asset-freeze risk!
Allocated vs Unallocated Bullion & The Sovereign Custody Repatriation Shift#
Following the February 2022 G7 immobilization of ~$300 billion in Russian central bank foreign-currency securities, reserve committees across emerging Asia, the Middle East, and Central Europe overhauled both asset allocation AND physical vaulting jurisdiction:
- Strict Allocated Bar Ownership: Central banks refuse "unallocated" commercial bullion-bank metal credits (which represent unsecured general-creditor claims on a London bank). Official reserves demand fully allocated, serial-numbered 400-troy-ounce LBMA Good Delivery bars (995.0+ fine gold) segregated on custodial ledgers with zero rehypothecation.
- Tri-Hub Vaulting Split (Bank of England, NY Fed, Domestic Vaults): While the Bank of England's Threadneedle Street vaults (~5,300+ metric tons) and the Federal Reserve Bank of New York's Liberty Street bedrock vault remain essential for instant OTC liquidity, central banks in Poland, India, Hungary, Germany, and China repatriated hundreds of tons into domestic capital-city vaults—keeping 40%-50% in London for liquidity and 50%-60% onshore for sovereign immunity!
As mapped in our IMF COFER reserves and FX intervention hub and Central European CNB and NBP gold reserve buildouts, sovereign OTC purchases conducted quietly through Zurich/London refining channels or domestic mine off-take put a relentless structural bid under spot XAU/USD.
How Central Banks Monetize Gold Into Instant US Dollars via BIS Gold Swaps#
Critics often ask: "If a central bank holds physical gold instead of US Treasury Bills, how can it raise $5 billion of cash US dollars in 48 hours to defend its currency?" Enter the Bank for International Settlements (BIS) in Basel (BCBS / BIS)!
Provided a central bank holds allocated LBMA Good Delivery bars inside the Bank of England's London vault, it can execute a confidential loco-London Gold-for-USD Swap with the BIS (tracked periodically in BIS quarterly financial footnotes from 100 to 500 metric tons!):
- Near Leg (T+2): Sight-transfer title of allocated London bars at the Bank of England to the BIS account in exchange for hard cash US dollars wired to NY Fed/correspondent accounts.
- Far Leg (3M / 6M): Repay cash USD plus implied gold-lease-adjusted SOFR interest (SOFR - GOFO/GLR) and reclaim the exact allocated gold weight!
European Eurosystem central banks—including the European Central Bank, BaFin / Bundesbank framework, Banco de Portugal, OeNB Austria, and MNB Hungary—account for gold unrealized gains inside dedicated Gold Revaluation Accounts so spot gold volatility never distorts annual fiscal profit transfers to ministries of finance.
| Gold Reserve Custody Tier | Jurisdictional Immunity | T+2 USD Liquidity Speed | Typical Storage & Shipping Cost | Strategic Role in Reserve Tranche |
|---|---|---|---|---|
| Domestic Central Bank Vault | 100% Sovereign Immunity | Slow (requires airlift + assay to LDN) | ~0 bps internal security cost | Ultimate geopolitical tail-risk anchor |
| Bank of England (Loco London) | UK Sovereign / Diplomatic | Instant T+2 via BIS / LBMA swaps | ~1.5 - 3.0 bps/yr custody fee | Active liquidity & gold-lending hub |
| NY Fed Liberty Street Vault | US FSIA Central Bank Shield | Fast (requires bar-shape switch vs LDN) | Zero custody fee (handling only) | Legacy Bretton Woods European custody |
| Zurich / Bern Allocated Vaults | Swiss Neutrality (FINMA) | Fast T+2 refining & kilobar bridge | ~3.0 - 5.0 bps/yr commercial | Refining hub (converts 400oz <-> 1kg) |
Gold Swap Implied USD Funding Rate & Revaluation Buffer Math#
When a central bank swaps allocated loco-London bullion with the BIS or LBMA market-makers to raise 3-month US dollars instead of selling US Treasuries, its annualized dollar borrowing rate equals 3-month SOFR minus the 3-month Gold Lease Rate (r_{GLR}) (historically 15 to 45 bps positive lease pickup for the gold lender!):
- EffectiveUSDCostSwap = r{SOFR,3M} - r_{GLR,3M} (cheaper than unsecured USD borrowing!)
- GoldShareofReserves = ( Tonnes * 32,150.75 * Spot{XAU} ) / ( FXReserves{USD} + GoldValue{USD} )
- Worked 100-Metric-Ton Central Bank BIS Gold-for-USD Swap Calculation (Spot XAU = $2,650 / troy oz):
- 1 Metric Ton = 32,150.7466 troy oz -> 100 Tons = 3,215,075 oz * $2,650 = $8.520 Billion cash USD raised!
- 3M US SOFR = 3.85%; 3M Loco-London Gold Lease Rate r_{GLR} = +0.28% (28 bps lease yield earned on gold)
- Effective 3-Month USD Funding Cost = 3.85% - 0.28% = 3.57% annualized (28 bps BELOW SOFR & 53 bps below C7 swaps!)
Why Unreported Sovereign Gold Buying Creates Asymmetric XAU/USD Floors#
Comparing IMF International Financial Statistics (IFS) monthly reported central bank gold additions against World Gold Council (WGC) and UK HMRC Swiss/London customs export data reveals that only ~45% to 60% of sovereign gold buying is reported immediately in monthly IMF lines—with sovereign wealth agencies and state entities disclosing additions incrementally over quarters!
Portfolio Implications for G10 & EM Currency Reserve Ratios#
For FX strategists evaluating emerging-market currency vulnerability on our sovereign FX reserves & intervention hub, always include loco-London allocated gold alongside COFER FX securities when computing IMF ARA reserve adequacy buffers, while discounting domestically landlocked bullion by a 5-to-10-day airlift mobilization lag during acute spot pegs!
Frequently asked questions
Why did central banks accelerate physical gold buying after February 2022?
Freezing ~$300B of foreign-currency securities proved that sovereign bonds held in foreign clearing systems carry geopolitical immobilization risk, whereas domestically vaulted allocated bullion carries zero counterparty risk.
What is the difference between allocated and unallocated gold in central bank reserves?
Allocated gold grants outright legal title to specific numbered 400-oz physical bars stored in a segregated vault; unallocated gold is merely an unsecured balance-sheet claim against a commercial bullion bank.
How can a central bank use physical gold to defend its exchange rate without selling the gold?
By keeping a liquidity slice of allocated bars at the Bank of England, a central bank can execute a confidential 3-to-6-month Gold-for-USD swap with the BIS in Basel, raising billions in T+2 cash dollars.
Why do central banks buy 400-troy-ounce bars instead of 1-kilogram bars?
The 400-troy-ounce (~12.4 kg) LBMA Good Delivery bar is the wholesale institutional settlement standard across London, the BIS, and the Bank of England, avoiding kilobar recasting fees.
Publication record
- Published
- 14 November 2026
- Updated
- 14 November 2026
- Author
- Henrik Lindqvist, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Henrik Lindqvist, CFA. (2026, November 14). Central Bank Physical Gold Accumulation, Allocated Vaulting & BIS Gold Swaps. FXMacro Wire. https://fxmacrowire.com/wire/central-bank-gold-accumulation-allocated-vaulting-fxRelated Sovereign FX Reserves Intervention & Institutional Briefings
Explore Sovereign FX Reserves Intervention Hub (20) →Sovereign FX Reserves Intervention
IMF COFER Reserves, Sterilized FX Intervention & Sovereign Gold Guide (2026)Sovereign FX Reserves Intervention
IMF Special Drawing Rights (SDR): Basket Weights, SDRi Rate & FX AccountingSovereign FX Reserves Intervention
PBOC USD/CNH Daily 09:15 Parity Fixing, +/-2% Band & Counter-Cyclical FactorSovereign FX Reserves Intervention
MAS S$NEER Band Slope, Width & Re-Centering: Singapore Exchange-Rate PolicySovereign FX Reserves Intervention
Danmarks Nationalbank EUR/DKK ERM II Peg: Asymmetric Policy Spread DefenseSovereign FX Reserves Intervention
CNB Czechia & NBP Poland FX Reserves: Equity Tranches, Gold & EU InflowsSovereign FX Reserves Intervention
Portfolio-Balance vs Signaling Channels of Sterilized FX InterventionSovereign FX Reserves Intervention
US Treasury Semi-Annual FX Report: Three Manipulation Criteria & ESF RulesEm Carry Terms of Trade Shocks
USD/ZAR Proxy Hedging, SARB Inflation Target Shift & PGM Export BetasEm Carry Terms of Trade Shocks
USD/INR Volatility Compression: RBI Two-Way NDF Intervention & FAR Bond FlowsEm Carry Terms of Trade Shocks
FX Carry Crash Skewness: VIX & ICE BofA MOVE Regime-Switching SignalsEm Carry Terms of Trade Shocks
Brent Crude Oil Supply Shocks: Exporter vs Importer FX Divergence Math
FXMacro Wire Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.